Remortgage Solicitor: Your 2026 Legal Process Guide

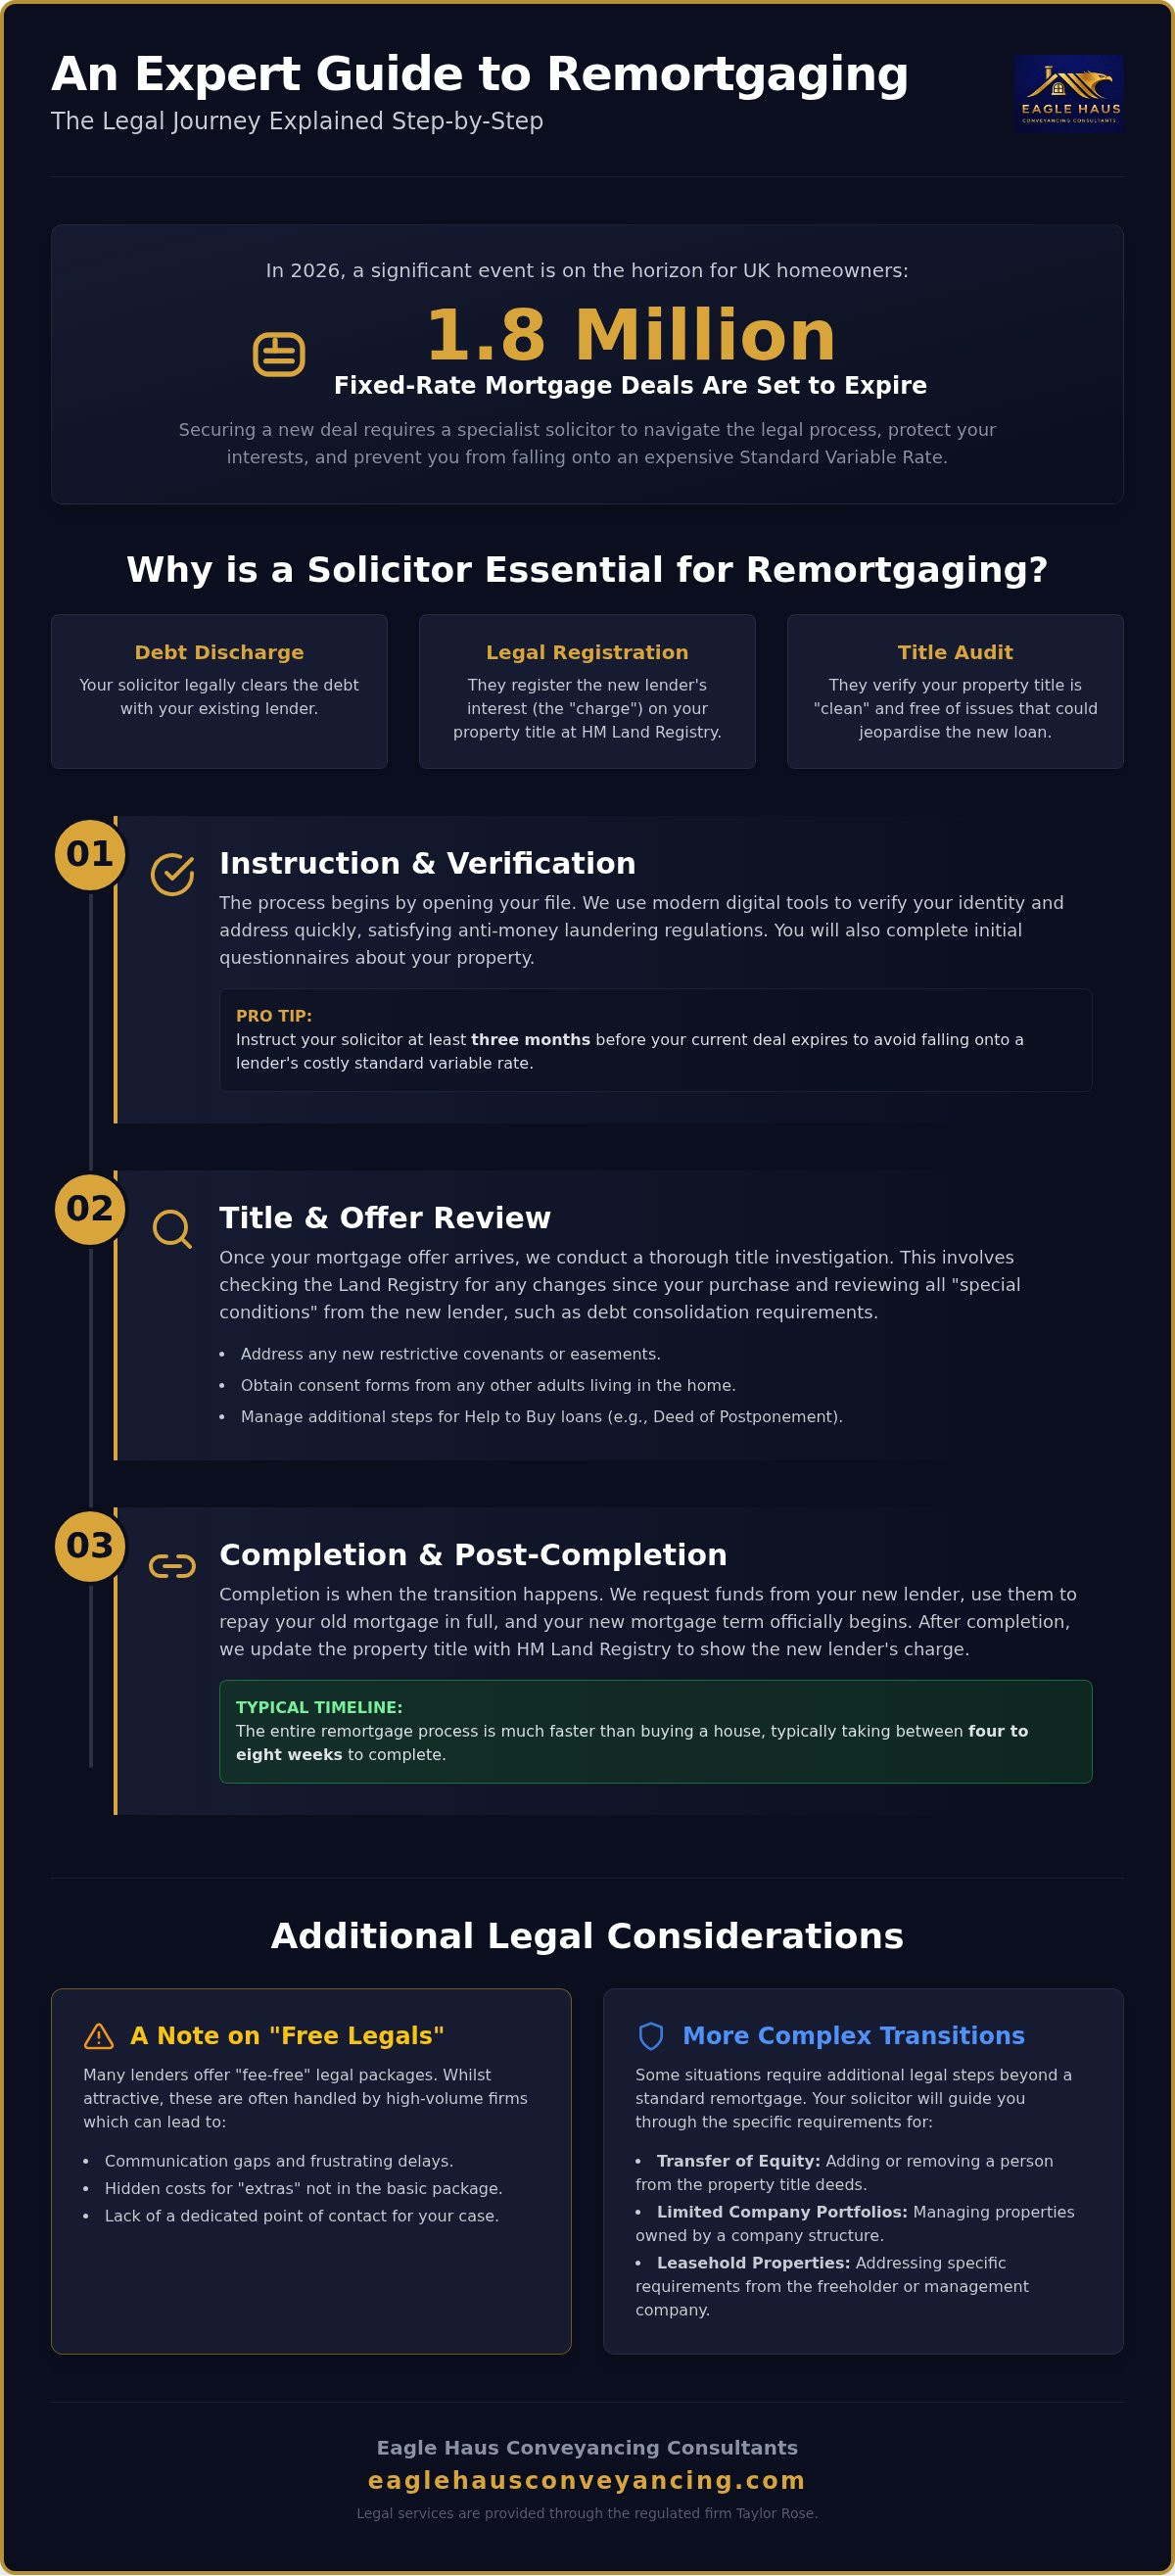
Did you know that approximately 1.8 million fixed-rate mortgage deals are set to expire across the UK in 2026? With the Bank of England base rate currently sitting at 3.75%, you're likely looking for a specialist solicitor for remortgage to help you secure a better interest rate before your current deal ends. It's natural to feel anxious about hidden legal fees or the risk of missing a strict mortgage offer deadline whilst you're trying to organise your finances. You might even feel confused about whether your situation requires a simple switch or a more complex transfer of equity.
We understand these pressures, and we're here to help you feel secure. Choosing the right legal partner is about more than just paperwork; it's a vital audit of your property title that ensures your transition to a new lender is seamless. Discover exactly how a specialist manages your legalities to ensure a swift, secure, and stress-free process with no surprises at the point of completion. This guide previews the 2026 legal timeline and explains how our modern, tech-savvy approach through the regulated firm Taylor Rose keeps your remortgage moving forward without the usual stress.
Table of Contents
Why Do You Need a Solicitor for a Remortgage?
When you decide to switch lenders, the process involves more than just signing a new contract. A specialist solicitor for remortgage is required because the legal "charge" on your property must be updated. Your solicitor acts as the essential bridge between your old lender and your new one. They ensure the existing debt is fully discharged and the new lender’s interest is correctly registered at HM Land Registry. With 1.8 million fixed-rate deals set to expire across the UK in 2026, having a proactive legal partner is vital to avoid falling onto a lender's expensive Standard Variable Rate.
You might ask, What is a remortgage? at its core. It's the process of replacing one mortgage with another using the same property as security. Because the property is the security, the new lender needs absolute certainty that the title is "clean." Your solicitor verifies there are no unexpected restrictions, such as new charges or legal disputes, that could jeopardise the lender's investment. In most UK transactions, the same solicitor acts for both you and the lender to keep the process efficient and secure.
The Legal Difference Between Remortgaging and Moving House
Remortgaging is typically much faster than buying a new home. Since there's no "chain" of buyers and sellers to coordinate, the timeline is significantly compressed. You aren't waiting for someone else to sell their house before you can complete yours. The focus also shifts; while a house move involves intensive checks on property condition, a remortgage prioritises title validity and lender requirements. It's a streamlined legal audit rather than a full-scale acquisition, often taking between four and eight weeks to reach completion.
When "Free Legals" Might Not Be Free
Many lenders offer "fee-free" packages to entice borrowers. While this sounds attractive, these lender-appointed firms often operate on a high-volume basis. This can lead to communication gaps or frustrating delays during busy periods. You might also find hidden costs for "extras" like bank transfer fees or leasehold supplements that aren't covered in the basic package. Choosing an independent specialist, such as Eagle Haus where legal services are provided through the regulated firm Taylor Rose, gives you a dedicated point of contact. This personal connection is especially valuable if you have a complex case or require local knowledge of the Staffordshire and West Midlands market.
The Remortgage Conveyancing Process: A Step-by-Step How-To
Understanding the legal journey helps remove the anxiety of the unknown. When you instruct a solicitor for remortgage, the process follows a methodical path designed to protect your property rights and satisfy your new lender's requirements. At Eagle Haus, we use modern digital verification tools to streamline these stages, ensuring your file moves quickly from instruction to registration. Our goal is to make the transition feel like a simple update rather than an administrative burden.
Step 1: Opening Your File and Initial Checks
To begin, you'll need to provide proof of identity and address to satisfy anti-money laundering regulations. We use tech-savvy solutions to make this as simple as possible, often allowing you to verify your documents from your smartphone. You'll also complete initial questionnaires about your property and current mortgage details. It's best to start this process at least three months before your current deal expires. Early instruction is the most effective way to avoid the "reversion rate" trap, where you're forced onto a lender's standard variable rate whilst waiting for paperwork to clear.
Step 2: Title Review and Lender Conditions
Once your mortgage offer arrives, your solicitor performs a thorough title investigation. This involves checking the Land Registry for any changes since you originally purchased the home, such as new restrictive covenants or easements. If you have a Help to Buy loan, you should consult the official government guidance on remortgaging to understand the additional steps required, such as obtaining a Deed of Postponement. We also address "special conditions" in your offer, such as requirements for debt consolidation or specific property repairs. If other adults live in the home, they'll need to sign occupiers' consent forms to ensure the new lender has priority.
Step 3: Completion and Post-Completion
Completion day is when the actual transition happens, and it's often the part of the process that causes the most confusion. Your solicitor requests a final redemption statement from your current lender to calculate the exact payoff amount, including any daily interest. We then prepare a Completion Statement, which provides a clear, line-by-line breakdown of all funds. On the day itself, we draw down the money from your new lender, pay off the old mortgage, and handle the distribution of any surplus funds to your bank account. Finally, we update the Land Registry to show your new lender as the primary charge holder. For a stress-free experience, you can start your journey with us today. All legal services are provided through the regulated firm Taylor Rose, giving you peace of mind throughout the transition.
Navigating Remortgage Legal Fees and Disbursements
Transparency is the foundation of a stress-free transition to a new lender. When you're comparing options for a solicitor for remortgage, it's vital to distinguish between professional legal fees and third-party disbursements. Professional fees cover the expert time spent investigating your title and liaising with lenders, whilst disbursements are costs your solicitor pays to external organisations on your behalf. We believe in clear, upfront communication so you can budget with absolute confidence and avoid any surprises on your final completion statement.
One of the most significant disbursements is the HM Land Registry fee. For a standard remortgage, these are calculated using "Scale 2" rates. In 2026, choosing a tech-savvy firm that uses electronic applications can save you money; for instance, a property valued between £200,001 and £500,000 incurs an electronic fee of £45, compared to £100 for a traditional postal application. We always prioritise these efficient digital routes to keep your costs as low as possible.
Common Disbursements in a Remortgage
Beyond the Land Registry, several smaller costs are mandatory for almost all UK lenders. These ensure the security of the loan and the validity of the transaction:
Official Copy Entries: These are the digital documents obtained from the Land Registry that prove you own the property and show any current charges.
Bankruptcy Searches: A mandatory check required by lenders to confirm that no party involved in the mortgage is currently subject to bankruptcy proceedings.
Bank Transfer Fees: The cost of using the CHAPS system to move large sums of money securely and instantly between banks on the day of completion.
You might also be offered Search Indemnity Insurance as an alternative to full local authority searches. Whilst full searches are essential when buying a home, many lenders accept indemnity insurance for a remortgage. This is often faster and more cost-effective, providing the lender with protection against potential local issues without the weeks of waiting for a council response.
How to Get an Accurate Remortgage Quote
To receive a quote that truly reflects your situation, you should provide your estimated property value and the new loan amount from the outset. It's also helpful to mention if the property is leasehold or if you're dealing with a gifted deposit, as these require additional legal work that may carry a supplement. For a deeper dive into how legal costs are structured, you can read our Conveyancing Solicitor Fees: A Transparent 2026 Guide for Home Movers.
At Eagle Haus, we provide fixed-fee quotes to ensure you have a clear understanding of the legal timeline and costs. By choosing a partner where legal services are provided through the regulated firm Taylor Rose, you gain the security of a national firm with the personal touch of a boutique service. We're here to ensure your move to a better interest rate is as simple and affordable as possible.
Remortgaging with a Transfer of Equity or Company Structure
Remortgaging often serves as the perfect catalyst for updating property ownership. Whether you're adding a spouse to the title deeds or removing a former partner, combining these legal steps is a strategic move that saves time and reduces overall costs. When you instruct a solicitor for remortgage to handle a transfer of equity simultaneously, you avoid paying for two separate registration processes at HM Land Registry; this streamlines the administrative burden and keeps your legal timeline on track.
It's a common misconception that Stamp Duty Land Tax (SDLT) only applies when you're buying a new home. In a transfer of equity, if the "consideration" (the value of the mortgage debt being taken on plus any cash payment made) exceeds the current threshold, you may still have a tax liability. We help you identify these requirements early in the process to ensure your financial planning remains accurate and there are no surprises at the point of completion.
Combining a Remortgage and Transfer of Equity
This is frequently the most cost-effective time to change ownership because your new lender must approve the new structure as part of the mortgage offer anyway. Your solicitor ensures that the new deed reflects the correct ownership shares, whether you choose to be joint tenants or tenants in common. If you're navigating these changes, our Transfer of Equity Legal Help: Your 2026 Guide to Changing Property Ownership provides a deeper look at the specific requirements for different scenarios.
Limited Company Remortgages for Investors
For property investors, 2026 continues to see a trend towards moving personal portfolios into limited company structures for tax efficiency. This transition is legally complex, involving a "sale" from yourself to your company whilst simultaneously arranging new finance. Specialist conveyancing is required here, particularly when dealing with bridging loans or portfolio refinancing. You can explore the details of this process in our guide on Company Purchases: A Professional Guide to Limited Company Conveyancing in 2026.
In multi-party transactions, lenders frequently require Independent Legal Advice (ILA). This ensures that anyone being added to or removed from a mortgage title fully understands their legal obligations without any conflict of interest. It's a protective measure that builds security for everyone involved. If you're ready to update your property ownership alongside your new mortgage deal, contact Eagle Haus today to discuss your requirements. All our legal services are provided through the regulated firm Taylor Rose, ensuring your investment is handled with the highest level of professional care.
Expert Remortgage Solicitors in Staffordshire and the West Midlands
Choosing a specialist solicitor for remortgage who understands the specific nuances of the West Midlands property market can significantly accelerate your completion. Whilst national firms often treat every case with a one-size-fits-all approach, a partner with local roots provides a more nuanced service. At Eagle Haus, we combine this boutique, personalised attention with the robust security of a large firm. All our legal services are provided through the regulated firm Taylor Rose, ensuring you receive the highest standard of professional care whilst benefitting from our deep local expertise.
Our team provides a proactive service for clients across Wolverhampton, Birmingham, and Telford. We understand that your home is your most significant asset, and your remortgage is a vital tool for your financial health. By blending modern, tech-savvy communication with traditional reliability, we ensure you're never left wondering about the status of your file. We position ourselves as your partner in this transition, aiming to build a sense of security through clear, honest communication from the moment you receive your initial quote.
Why Local Knowledge Matters in Conveyancing
Local knowledge is about more than just knowing the geography; it's about understanding the specific requirements of local authorities. For instance, search variations and turnaround times in Cannock or Walsall can differ significantly from those in Shropshire. A solicitor familiar with these local hubs can anticipate potential delays and manage lender expectations more effectively. This familiarity also extends to local surveyors and estate agents, allowing for faster, more informal communication that keeps your case moving forward. This "local first" approach provides a supportive environment where your specific situation is identified and prioritised, rather than being lost in a high-volume system.
Secure Your 2026 Remortgage Today
With the Bank of England base rate currently at 3.75% and 1.8 million fixed-rate deals expiring throughout 2026, acting early is essential. Interest rates remain in flux, and the difference between a smooth transition and falling onto a lender's standard variable rate often comes down to the speed of your legal team. We simplify the execution of your mortgage deed through secure digital platforms, making the process effortless for busy professionals. If you're looking for a partner who understands the regional market, our guide on Property Solicitors Near Me: A 2026 Guide to Choosing the Right Conveyancing Partner explains how to find the perfect fit. Don't leave your financial transition to chance; start your journey with a bespoke legal consultation today and secure your property's future with confidence.
Take the Next Step Toward a Secure Remortgage
Securing a better interest rate in 2026 is a vital financial move, but the legal process shouldn't be a source of anxiety. By understanding the importance of a thorough title audit and a clear legal timeline, you can move toward completion with total confidence. We've explored how early instruction prevents the "reversion rate" trap and why fee transparency is the foundation of a successful transition. Whether you're a homeowner in Wolverhampton or a property investor in Birmingham, choosing the right solicitor for remortgage ensures your interests are protected whilst your old debt is legally cleared.
At Eagle Haus, we provide regulated legal services through the firm Taylor Rose, combining national security with a boutique, client-focused approach. Our fixed-fee guarantee means you won't face hidden disbursements; you'll receive a clear breakdown of costs from the very start. As specialists in West Midlands property law, we're here to manage the complexities of your transition so you don't have to. Ready to get started? Get a Transparent Remortgage Conveyancing Quote from Eagle Haus today. We look forward to guiding you through a swift and stress-free process.
Frequently Asked Questions
Do I really need a solicitor to remortgage my house?
Yes, a solicitor is essential when you switch to a new lender. They manage the legal discharge of your current mortgage and ensure the new lender’s interest is correctly registered at HM Land Registry. This process protects your property rights and satisfies the lender's security requirements. At Eagle Haus, we provide these regulated legal services through Taylor Rose, ensuring every detail is handled with professional care for homeowners across Staffordshire and the West Midlands.
How long does the legal process for a remortgage take in 2026?
A typical remortgage process in 2026 takes between four and eight weeks to complete. This timeline depends on how quickly your new mortgage offer is issued and how fast your current lender provides a redemption statement. Starting the process three to six months before your current deal expires is the best way to avoid moving onto a standard variable rate. Our modern, tech-savvy approach helps keep this timeline moving efficiently for clients in Wolverhampton and Birmingham.
What are the typical solicitor fees for a remortgage?
Professional fees for a solicitor for remortgage vary based on the complexity of your property title, such as whether it's freehold or leasehold. You'll also pay third-party disbursements, including Land Registry fees and bankruptcy searches. We believe in total transparency and provide fixed-fee quotes to ensure there are no surprises at the point of completion. This allows you to budget accurately whilst benefitting from our local expertise across Telford and Shropshire.
Can I remortgage and add my partner to the deeds at the same time?
Yes, combining a remortgage with a transfer of equity is a common and cost-effective way to change property ownership. Your solicitor manages the legal paperwork to add or remove a name from the title deeds whilst simultaneously arranging the new finance. This requires careful coordination with your new lender to ensure they approve the new ownership structure. We specialise in these multi-party transactions for clients in Cannock, Walsall, and the wider West Midlands region.
Will my solicitor need to do searches again if I am remortgaging?
It depends on your new lender’s specific requirements. Whilst some lenders insist on full local authority searches, many accept search indemnity insurance for remortgages. This insurance is often faster and more cost-effective, protecting the lender against potential issues without the wait for council responses in areas like Staffordshire. We'll review your mortgage offer to confirm which option is best for your situation, ensuring a swift transition to your new interest rate.
What happens on the day of remortgage completion?
On completion day, your solicitor for remortgage receives the funds from your new lender and uses them to pay off your existing mortgage debt in full. Any surplus funds, minus legal fees and disbursements, are then transferred directly to your bank account. We also handle the final administrative steps, such as updating HM Land Registry with the new charge. Our proactive team ensures this transition is seamless for residents across Wolverhampton and Birmingham, providing a secure finish.
Do I need a solicitor if I am staying with the same lender (Product Transfer)?
If you're simply switching to a new deal with your existing lender, known as a product transfer, a solicitor is generally not required. This is because the legal charge on your property remains with the same institution, so there's no need to update the Land Registry or discharge a debt. However, if you wish to change the ownership structure at the same time, you'll still need professional legal support to manage the transfer of equity.
Can a solicitor help with a bridging loan remortgage?
Yes, we specialise in the complex legal requirements of bridging loan remortgages for property investors and businesses. These transactions often move at a faster pace and require a high level of technical expertise to ensure all financial legalities are met. Whether you're refinancing a portfolio in Shropshire or securing a company-based purchase in Walsall, we provide the regulated legal services through Taylor Rose needed to facilitate these high-stakes property investments securely and efficiently.
Comments