Remortgage Legal Fees: A Comprehensive 2026 Guide to UK Costs

The "free" legal package offered by your lender might actually be the most expensive mistake you make during your 2026 property transition. Whilst saving on upfront costs sounds ideal, the hidden price often includes weeks of delays and poor communication that could leave you stuck on a high standard variable rate. Understanding the reality of remortgage legal fees is the only way to ensure you're actually saving money when you switch deals.
We know that remortgaging is often about finding financial breathing room, yet the process itself can feel surprisingly stressful when costs aren't clear from the start. You're likely looking for a straightforward way to budget without worrying about "admin" fees appearing at completion or confusing terminology like disbursements and office copies. This guide provides a clear breakdown of the total legal bill for 2026, covering everything from professional solicitor fees to those small but essential costs that often go unmentioned. We'll show you how to navigate the transition between lenders smoothly; so you can lock in your new rate with total confidence and zero surprises.
Table of Contents
Understanding Remortgage Legal Fees: What to Expect in 2026
When you prepare to switch lenders, your completion statement will typically show remortgage legal fees split into two distinct categories. The first is the professional fee, which covers the solicitor's time and expertise in managing the transition. The second category includes disbursements, which are costs paid to third parties for essential services like Land Registry updates. Whilst remortgaging is generally faster than a property purchase, it's still a formal legal process that requires a change of title at the Land Registry.
Homeowners often ask, What is a remortgage? and why does it require a solicitor? Essentially, it's the act of replacing your current mortgage with a new one, often to secure a better interest rate or release equity. Even though you already own the home, the new lender needs to ensure their financial interest is legally protected. In 2026, the modern standard for these services is a fixed-fee model. This approach provides budget certainty from the outset, ensuring you aren't met with unexpected hourly charges at the end of the process.
Why Do You Need a Solicitor for a Remortgage?
A solicitor acts as the essential bridge between you and your new lender. Their primary responsibility is to verify the identity of all borrowers, a critical step that prevents mortgage fraud and protects your property's security. They also conduct specific searches required by the new lender to ensure there are no issues with the property that could affect its value. Once the new mortgage offer is ready, the solicitor manages the redemption of your existing loan and ensures the new charge is correctly registered. This diligent oversight prevents administrative errors that could lead to your old mortgage remaining on the title deeds by mistake.
The 2026 Market: How Prices Are Calculated
The cost of your legal work isn't a flat rate across the board. Instead, it's often calculated on a sliding scale that reflects the property's market value and the complexity of the title. For example, a leasehold property usually involves more intensive legal work than a freehold home, as the solicitor must review the lease terms and liaise with the freeholder. Specialist cases, such as bridging loans or remortgaging through a limited company, also require a higher level of technical expertise. It's also vital to ensure your chosen firm is on your specific lender’s approved panel, as this avoids the extra cost and delay of the lender appointing their own separate legal representative.
The Breakdown: Professional Fees vs. Third-Party Disbursements
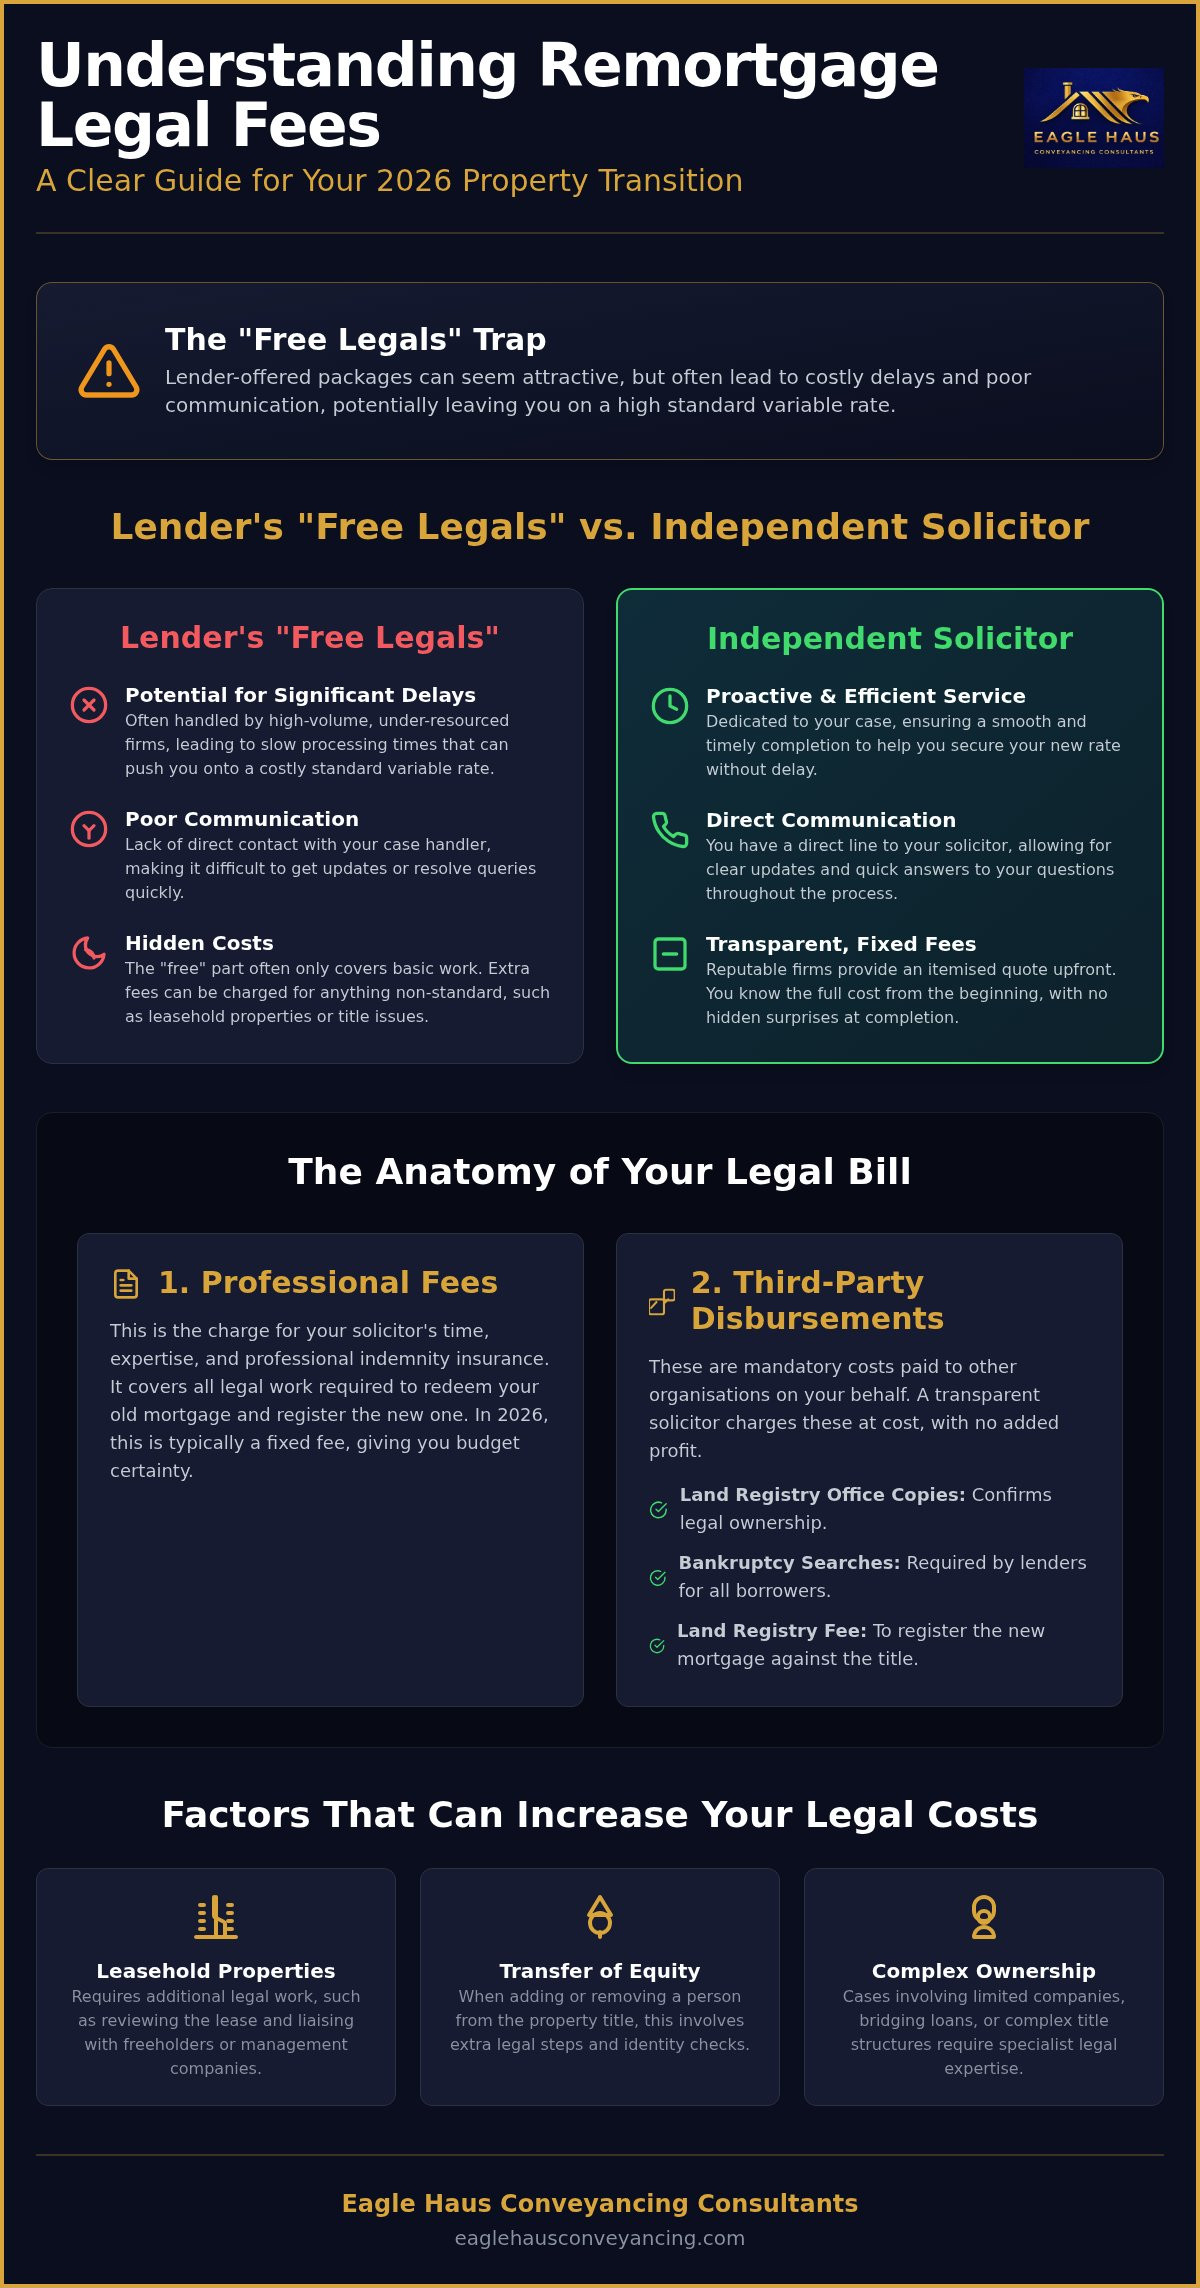
When you receive a quote for remortgage legal fees, it's easy to feel overwhelmed by the list of individual charges. To simplify things, you can divide your bill into two clear buckets. Professional fees represent the payment for your solicitor's dedicated time and legal expertise. On the other hand, disbursements are mandatory costs that your solicitor pays to third parties on your behalf. A transparent firm will always charge disbursements at cost, meaning they don't add a profit margin to these specific items. Whilst some firms might bundle these into a single figure, seeing them itemised ensures you aren't overpaying for standard administrative tasks.
Common Disbursements Explained
Most standard remortgages involve a predictable set of disbursements. These are non-negotiable fees required to satisfy the new lender's security requirements and update the official record of your property ownership.
Land Registry Office Copies: This is a small fee paid to obtain the official "snapshot" of your title deeds from HM Land Registry. It confirms you are the legal owner and shows any existing charges that need to be cleared before the new mortgage can be registered.
Bankruptcy Searches: Lenders require a search against each borrower to ensure there are no pending insolvency issues. This protects the lender's priority over the property and is a standard requirement for every UK mortgage.
Land Registry Registration Fee: Once the remortgage completes, your solicitor must update the digital deeds to reflect the new lender. The cost depends on the value of the mortgage and the method of submission; with electronic applications usually being more cost-effective.
Optional or Variable Costs
Some costs depend on your specific lender's policy or the nature of your property. Understanding these variations helps you compare quotes more accurately and avoid surprises during the final stages of the process.
Local Authority Searches: Whilst some lenders insist on full searches, many now accept "No-Search Indemnity Insurance". This is often cheaper and significantly faster; allowing you to move towards completion without waiting on council response times.
AML (Anti-Money Laundering) Checks: Modern firms use digital verification tools to confirm your identity securely. This tech-savvy approach is faster than traditional methods and provides a higher level of security for your personal data.
Electronic Transfer Fees: This covers the cost of using the CHAPS system to move large sums of money between banks on the day of completion. It ensures the funds arrive instantly so your old mortgage can be paid off without any gap in interest.
If you're looking for a clear, itemised breakdown of these costs for your specific situation, you can get a transparent remortgage quote that avoids hidden surprises. Having this clarity from the start is the best way to maintain control over your finances and ensure a smooth transition between lenders.
Lender "Free Legals" vs. Independent Solicitors: The Real Cost
Many lenders entice borrowers with the promise of "free legals" to lower the initial cost of switching deals. Whilst this sounds like a significant saving, these services are frequently outsourced to high-volume firms often described as "conveyancing factories". In these environments, the lender pays your remortgage legal fees, but you may pay a different price in terms of communication and speed. These firms often operate on a scale that makes individual attention difficult to maintain, leading to a process that feels impersonal and reactive. Choosing an independent solicitor is increasingly seen as the premium choice for homeowners who prioritise a swift, transparent transition over a zero-upfront-cost package.
The Hidden Downsides of Free Legal Services
Working with a high-volume firm often means you won't have a dedicated file handler. You might find yourself repeating your property details to a different person every time you call for an update, which is both frustrating and time-consuming. These firms are typically set up for standard, "vanilla" remortgages. If your situation requires non-standard work, such as a Transfer of Equity or addressing complex title issues, the free service often won't cover the extra work required. You could also face "hidden" costs, where simple tasks like digital ID verification are charged at a premium rate to help the firm recoup its costs. The most significant risk is the potential for delay. If the process stalls, you might miss your mortgage offer expiry date, which could leave you stuck on a high standard variable rate whilst you wait for the paperwork to clear.
When Is a Fixed-Fee Independent Solicitor Better?
Selecting an independent, fixed-fee solicitor is often the smarter move if you are on a tight deadline to avoid a rate hike. It's also the proactive choice if your property is leasehold or involves unregistered land, as these scenarios require more meticulous legal oversight than a standard freehold. Modern, independent firms tend to be more tech-savvy, using streamlined communication tools to keep you updated in real-time without you having to chase them. This level of service ensures that your remortgage legal fees represent a clear investment in reliability and efficiency rather than just another administrative hurdle. Choosing an independent solicitor provides the personal attention and professional accountability you need to navigate your financial transition with total peace of mind.
Factors That Can Increase Your Remortgage Conveyancing Costs
Whilst a standard switch between lenders is often straightforward, not all properties or ownership structures are the same. Certain scenarios require more intense legal oversight, which is why remortgage legal fees can vary between different quotes. Complexity usually stems from the amount of third-party coordination required or the additional risks your solicitor must manage. For instance, remortgaging a property held in a limited company name involves extra due diligence. Your solicitor must verify corporate standing and ensure the new charge is registered at both Companies House and the Land Registry, adding a layer of technical work that a standard personal remortgage doesn't require.
You might wonder why a quote is higher if you're simply "changing names" on a mortgage. The reality is that the legal work involves far more than just updating a digital record. It requires a full investigation of the title, a formal transfer of legal interest, and ensuring the new lender's security is absolute. This level of professional diligence protects your home just as much as it protects the bank's investment. It's about ensuring every detail is legally sound to prevent future disputes or title issues.
Remortgage with Transfer of Equity
If you're adding or removing a partner from your deeds during the process, your solicitor must perform a separate Eagle Haus Transfer of Equity. This is a distinct legal action that runs alongside your remortgage. It involves drafting a formal Transfer Deed and, crucially, assessing potential Stamp Duty Land Tax (SDLT) implications. Even if no money changes hands, the "consideration"—the value of the mortgage debt being taken on—could trigger a tax bill. Having a specialist manage this ensures you don't fall foul of HMRC rules whilst trying to organise your finances.
Leasehold and Shared Ownership Nuances
Leasehold properties naturally involve more administration. Your solicitor must review the lease terms to ensure they meet your new lender's specific criteria, which can change as market regulations evolve. They also need to serve a "Notice of Charge" to the landlord or management company once the new mortgage is in place. Shared ownership adds another layer of complexity; your solicitor must navigate housing association rules and obtain their formal consent before the remortgage can proceed. Eagle Haus specialises in these complex transactions across the West Midlands, providing the local expertise needed for properties in Birmingham, Wolverhampton, and Staffordshire.
If your situation involves complex ownership or leasehold details, you can request a bespoke remortgage quote that reflects your specific needs without hidden surprises or completion-day delays.
Getting an Accurate Remortgage Quote in the West Midlands
Finding a quote that covers every eventuality is the best way to ensure your 2026 budget remains intact. When you compare remortgage legal fees, you should look beyond the headline figure. Some firms attract clients with a low base price; only to add "essential" extras later in the process. To avoid this, always ask for an all-inclusive breakdown that accounts for your specific property type. A transparent quote should include VAT, Land Registry fees, and any administrative charges for identity verification or electronic transfers. By securing this clarity upfront, you protect yourself from completion-day surprises that could eat into your mortgage savings.
Use this checklist when reviewing your conveyancing quotes to ensure you are comparing like-for-like:
Does the quote include the Land Registry registration fee based on your property value?
Are there additional supplements for leasehold or shared ownership properties?
Is the cost of electronic money transfers clearly stated?
Are digital ID and AML (Anti-Money Laundering) checks included in the professional fee?
Is the firm on your new lender's approved panel to avoid extra representation costs?
Why Local Expertise Matters in Staffordshire and Shropshire
In areas like the Black Country or parts of Staffordshire, local knowledge isn't just a bonus; it's a necessity. Properties in these regions often require specific mining searches to satisfy lender requirements. A firm familiar with the West Midlands will anticipate these needs immediately, preventing the last-minute scrambles that often occur with generic national providers. Being able to access a local centre in Birmingham or Wolverhampton to verify original documents can also shave days off your completion timeline. This local connectivity often extends to your mortgage broker and estate agent, creating a joined-up approach that keeps your remortgage moving at pace. We understand the local landscape, which allows us to navigate regional land registry nuances whilst providing the modern, tech-savvy service you expect.
Next Steps: Securing Your 2026 Remortgage
As soon as your mortgage offer is issued, you should instruct your solicitor to begin the work. Having your digital ID and source of funds documentation ready will allow your legal team to clear the initial regulatory hurdles instantly. Modern conveyancing is about blending this proactive preparation with smart technology. At Eagle Haus, we use streamlined digital platforms to handle the heavy lifting of data collection, whilst ensuring you always have a human expert to talk to when you need guidance. We're here to make the transition between lenders as simple and stress-free as possible, allowing you to enjoy the benefits of your new rate without the administrative headache. Once you have your offer in hand, the path to a better deal is just a few clear steps away.
Secure Your Financial Future with Confidence
Budgeting for your 2026 property transition doesn't have to be a guessing game. By distinguishing between professional charges and third-party disbursements, you can maintain total control over your remortgage legal fees from the very first day. We've explored how choosing an independent solicitor over a "free" factory-style firm prioritises speed and clear communication; ensuring you don't miss out on better rates due to administrative delays. Whether you're navigating a leasehold property or a complex transfer of equity, the right legal partner makes all the difference to your completion timeline.
At Eagle Haus, we blend a modern, proactive communication style with deep-rooted expertise in West Midlands property law. Our services are regulated through Taylor Rose, providing you with the security of a large firm and the personal attention of a boutique consultant. If you're ready to move forward without the stress of hidden costs, get a transparent, fixed-fee remortgage quote from Eagle Haus today. We're here to guide you through every step of the process, making your transition to a new lender as smooth and efficient as possible.
Frequently Asked Questions
Do I have to pay remortgage legal fees upfront?
You generally don't pay the full amount at the start of the process. Most solicitors require an initial payment to cover third-party disbursements; such as digital identity checks and Land Registry title copies. The remaining professional fee is typically settled as part of the final completion statement when your new mortgage funds arrive. This ensures you only pay for the bulk of the legal work once the transition is successfully finalised.
How much are typical Land Registry fees for a remortgage in 2026?
Land Registry fees are calculated on a sliding scale based on the value of your new mortgage loan. These costs remain dependent on whether your solicitor submits the application electronically or via post; with digital submissions being significantly more cost-effective. Your solicitor will confirm the exact fee based on the current HM Land Registry fee scales for the value of your specific property and mortgage.
Can I use the same solicitor who did my original house purchase?
You can use your previous solicitor as long as they are on your new lender's approved panel. Many homeowners find this helpful because the firm already has a record of the property's title and your previous identity checks. It's always worth checking the panel status early to avoid having to switch firms halfway through your application process if your new lender has a restricted list of approved conveyancers.
What happens to the legal fees if my remortgage falls through?
If the process falls through; you'll usually be responsible for any disbursements already paid to third parties. This includes costs for searches or Land Registry documents that have been completed. Whilst some firms offer a "no completion, no fee" arrangement for their professional time, you should always review your initial instruction letter to see which specific costs are protected and which remain payable if the deal stops.
Is it cheaper to remortgage with my current lender (Product Transfer)?
A product transfer is almost always cheaper than a full remortgage because it doesn't involve a change of legal title. Since you're staying with the same lender, there's no need for new remortgage legal fees or Land Registry updates. However, whilst it's cheaper in fees, you should always compare the interest rate savings of switching lenders to see which option provides the best long-term financial value.
Who pays the legal fees in a remortgage — the lender or the borrower?
The borrower is typically responsible for paying the remortgage legal fees. Some lenders offer "free legal" packages where they pay for a firm from their own panel to handle the work. Whilst this removes the upfront cost for you, it often means you have less control over the speed and communication of the process compared to instructing an independent solicitor who works directly for you.
How long does the legal part of a remortgage usually take?
The legal part of a remortgage typically takes between four and eight weeks to complete. This timeline depends on how quickly your new lender issues the mortgage offer and how fast the existing lender provides a redemption statement. Choosing a proactive, tech-savvy solicitor can help keep this process towards the shorter end of that scale by using modern digital communication tools to avoid postal delays.
Are remortgage legal fees tax-deductible for buy-to-let investors?
For buy-to-let investors, these costs are generally considered a deductible revenue expense. You can usually offset remortgage legal fees against your rental income when calculating your self-assessment tax return. Since these are costs associated with arranging finance for the business, they are treated differently than the capital costs of actually buying the property. You should always consult with a qualified accountant for specific tax advice tailored to your portfolio.


Comments