Gifted Deposit Conveyancing: 2026 Guide for UK Home Buyers

What if the generous gift meant to secure your first home actually becomes the very thing that stops your mortgage application in its tracks? It's a stressful thought, especially when your parents or loved ones are simply trying to help you onto the property ladder. Navigating gifted deposit conveyancing doesn't have to feel like an interrogation of your family's life savings, but many buyers still worry that a simple act of kindness will complicate their legal journey.
We've designed this 2026 guide to help you master the legal requirements, ensuring your purchase proceeds without unexpected delays or compliance issues. By following our proactive advice, you can protect your mortgage offer and provide your donors with clear, simple instructions. You'll gain the confidence to handle financial queries without the usual anxiety or confusion.
We'll walk you through the essential documentation your donors must provide, the impact of the June 2026 Anti-Money Laundering regulations, and how to clearly distinguish a gift from a loan to keep your lender satisfied. From the initial ID checks to the final exchange of contracts, this is your roadmap to a smooth, secure home purchase.
Table of Contents
Understanding Gifted Deposit Conveyancing in 2026
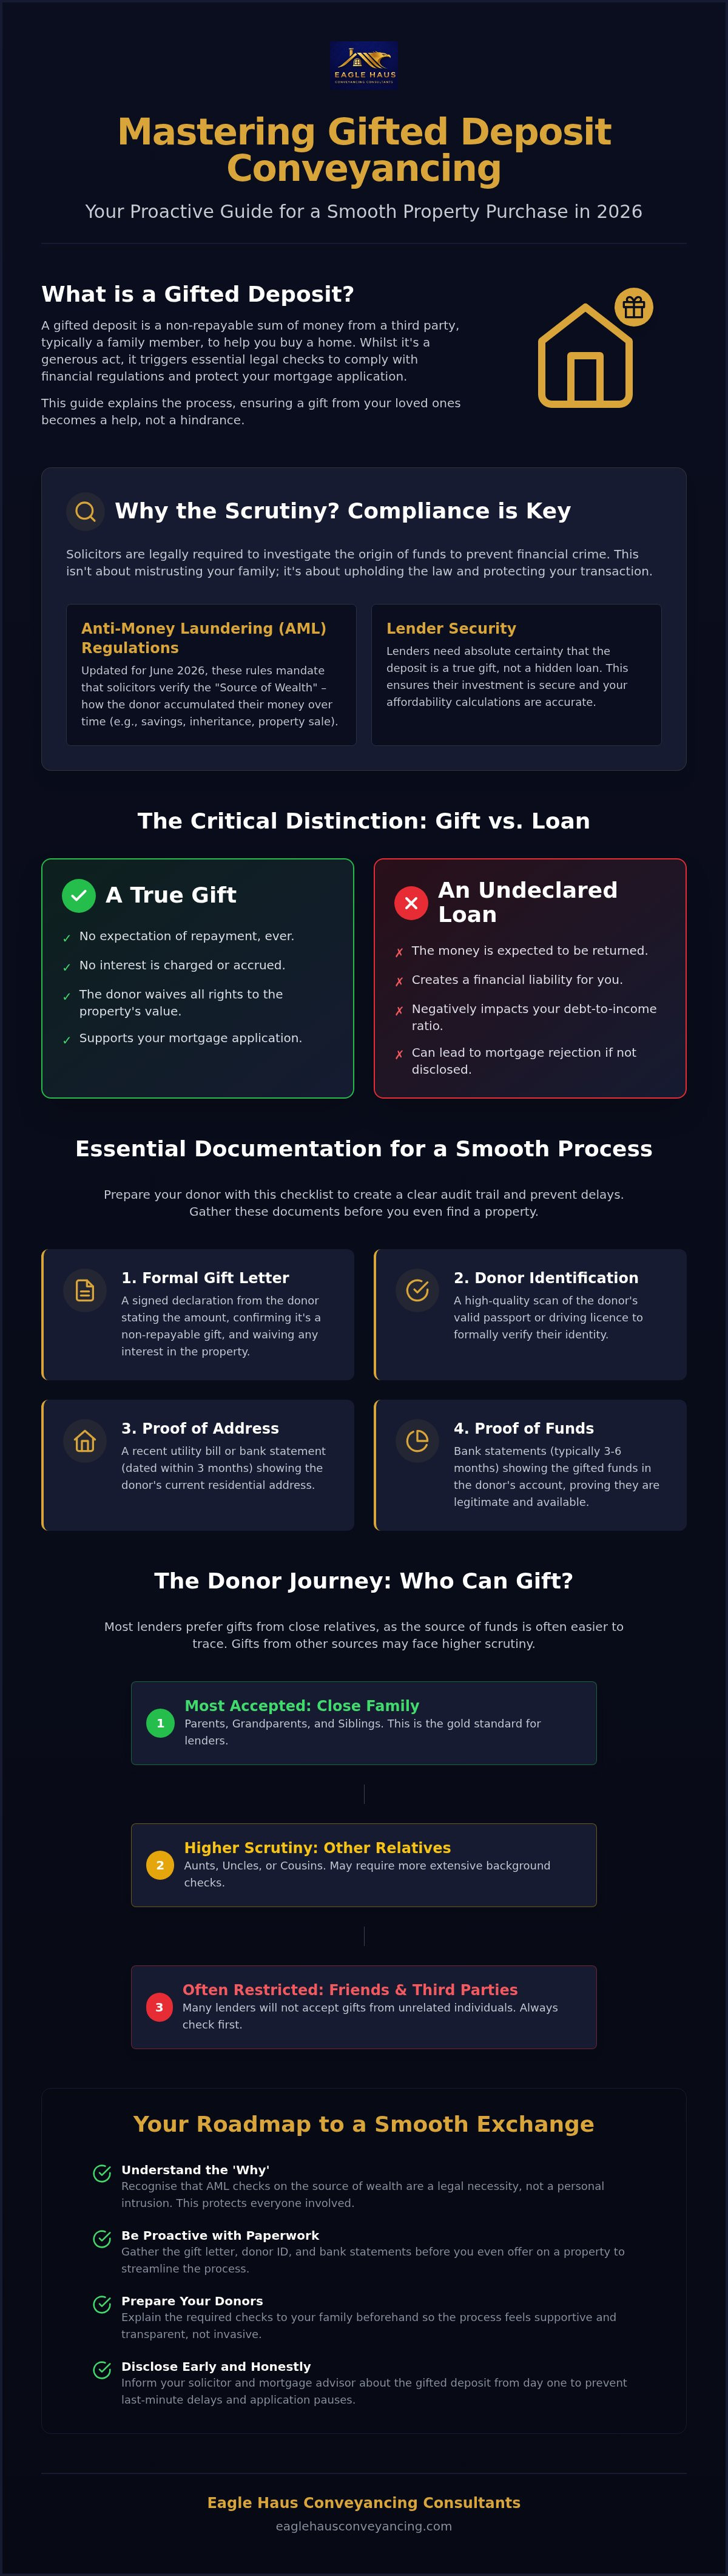
A gifted deposit is a sum of money provided by a third party to assist a buyer with their property purchase. Unlike a loan, this money is entirely non-repayable. It's a significant financial boost that helps many buyers bridge the gap between their personal savings and the rising costs of the UK property market. However, because this money didn't originate from your own salary or savings, it triggers specific legal checks that must be handled with care.
Solicitors are legally bound to investigate the "Source of Wealth" of the person giving the gift. This is a core part of modern anti-money laundering (AML) protocols. We need to understand how the donor acquired the funds over time, whether through decades of employment, a previous property sale, or perhaps an inheritance of their own. While these requests might feel intrusive, they're essential to protect the integrity of the financial system and your own transaction.
Most mortgage lenders prefer gifts from "close family" donors. This category typically includes parents, grandparents, and siblings. If a friend or a distant relative wants to help, they'll often face much higher levels of scrutiny. Some lenders may even restrict gifts from unrelated third parties entirely. Your solicitor will act as the bridge between your donor and the lender, ensuring everyone meets the necessary criteria for gifted deposit conveyancing to proceed.
The Legal Distinction: Gift vs. Loan
A true gift must come with no strings attached. If the person providing the funds expects the money back at a later date, even without interest, it's legally classified as a loan. This distinction is vital. A loan creates a financial liability that lenders must factor into your affordability and debt-to-income ratio. If you're already borrowing at your limit, an undeclared loan could lead to a mortgage rejection because the lender views it as an additional monthly debt.
Donors are also required to waive any beneficial interest in the property. In legal terms, a beneficial interest is a right to the value or use of the home. By signing a formal waiver, the donor confirms they have no right to live in the property or claim a portion of the proceeds when you eventually sell. This gives the lender total security over the asset.
Why Lenders Are Strict About Gifts in 2026
UK mortgage lenders have refined their criteria to ensure the conveyancing process is as secure as possible. The "Source of Funds" check is the final hurdle. This involves tracing the money from the donor's bank account directly to the solicitor's client account. It's a transparent trail that proves the money is legitimate and available.
To keep your purchase on track, you must be transparent about your funding from the very start. Early disclosure is the best way to prevent delays during the residential purchases and sales process. If a lender discovers a gift late in the transaction, they may pause the application to conduct their own manual reviews, which can take weeks. By being proactive, you ensure your lender has the information they need to approve your application without a second thought.
Essential Documentation for a Smooth Process
Organising your paperwork early is the most effective way to avoid delays. When you use a gift for your purchase, the legal team needs to build a clear audit trail that satisfies both the lender and UK regulators. This involves gathering documents from your donor that prove their identity and the legitimacy of their funds from the very start.
Your donor will need to provide a high-quality scan of their valid passport or driving licence. Alongside this, they must produce a utility bill or bank statement dated within the last three months to verify their current address. These steps are standard across the industry, as shown in this guide from Lloyds Bank on gifted deposit requirements, which highlights the need for transparency during the application.
Bank statements are usually required for a period of 3 to 6 months. This allows the solicitor to see the money sitting in the account or moving in from a verified source. It's best to provide full, unredacted statements to avoid follow-up questions that could slow down your gifted deposit conveyancing timeline.
What Must Be Included in the Gift Letter?
The gift letter is a formal declaration that protects you and your lender. It doesn't need to be long, but it must be precise. To be legally sound, the letter should include:
A clear statement that the money is an unconditional gift and not a repayable loan.
Confirmation that the donor will have no legal or equitable interest in the property.
The exact amount being gifted and the donor's relationship to you.
A signature from the donor, ideally witnessed by an independent adult.
Evidence for the Source of Wealth
There's a subtle but vital difference between where the money is now and how it was originally accumulated. While "Source of Funds" shows the money in a bank account, "Source of Wealth" explains the history behind it. If the gift comes from a pension lump sum, a property sale, or decades of monthly savings, your solicitor will need the corresponding evidence, such as a completion statement or a pension letter.
International gifts often face extra scrutiny. If your donors are based outside the UK, expect a more rigorous check of their local banking systems and potential translation requirements for their documents. Being proactive about these details ensures a smoother experience for everyone involved in the gifted deposit conveyancing journey. If you're feeling overwhelmed by the paperwork, our team can provide a clear checklist to help you and your family get organised quickly.
Comparing Gift Types: Pure Gifts vs. Alternatives
Not all financial help arrives as a simple lump sum of cash in a bank account. While "pure gifts" from parents remain the most common form of assistance, 2026 has seen a rise in creative arrangements that help buyers reach their goals. If you're receiving help from a friend rather than a relative, you should be prepared for deeper scrutiny. Most lenders are wary of non-family gifts because they worry about hidden commercial interests or future disputes over property ownership. Ensuring your gifted deposit conveyancing is handled by a team that understands these nuances is the best way to avoid a mortgage rejection.
For buyers looking at shared ownership houses, gifted deposits are an excellent way to secure an initial share. The legal process stays largely the same, but your solicitor must ensure the housing association is also happy with the gift source. This alignment between the lender, the landlord, and the solicitor keeps the transaction moving. Other options, like "Family Springboard" mortgages, allow parents to assist by placing savings in a locked account as security. While the money isn't technically "given away," the legal checks on the donor's identity and wealth still apply.
Vendor Gifted Deposits and New Build Incentives
Developers across the West Midlands, particularly on new estates in Telford or Cannock, often offer "Vendor Gifted Deposits." This is essentially a discount on the purchase price that the lender treats as your deposit. It's vital to remember that most lenders cap these incentives, usually at 5% of the total value. Your solicitor has a strict legal duty to report every incentive to your mortgage provider. Never try to hide a builder's "cash back" offer, as this can lead to your mortgage offer being withdrawn at the last minute.
Gifted Equity: Buying from Family at a Discount
Sometimes the gift isn't cash, but value. If you're buying a property from a family member at a price below its market value, this is known as "gifted equity." This often involves a transfer of equity at an undervalue. Because this can look like a way to hide assets from creditors, solicitors will usually require an "Insolvency Act Indemnity Policy." This insurance protects the lender if the donor goes bankrupt shortly after the gift is made. It's a small, one-off cost that provides essential peace of mind for everyone involved in the purchase.
The Donor Journey: Preparing Your Family
While you might be focused on property viewings and mortgage rates, your parents or grandparents are often the ones facing the most scrutiny. The donor journey is a vital part of gifted deposit conveyancing, yet it's frequently the source of the most friction. It's common for family members to feel that requests for bank statements and identity documents are an intrusion into their private lives. Explaining that these checks are a legal requirement for the solicitor, rather than a personal judgment, can help smooth the way.
Start the conversation early. Your family needs to know that the timeline for their checks will run alongside your own. If they're slow to provide documentation, the entire purchase can stall. You should also ensure they understand the "no-occupancy" rule. Most mortgage lenders require donors to sign a declaration confirming they won't live in the property. This is a non-negotiable point for many banks, and it's better to clarify this before any funds are transferred.
Independent Legal Advice (ILA) for Donors
In some transactions, a lender will insist that the donor speaks to their own solicitor. This is known as Independent Legal Advice (ILA). The goal is to protect the donor from "undue influence" and ensure they fully understand that the gift is absolute and non-repayable. While this adds a small layer of time and an extra fee to the process, it provides massive security. It proves the donor wasn't pressured into giving away their life savings, which protects both your relationship and the legal standing of your deposit.
Managing International Gift Complexity
If your gift is coming from outside the UK, the level of scrutiny increases significantly. Solicitors must conduct enhanced due diligence on funds arriving from foreign jurisdictions, especially those considered high-risk. This complexity often impacts first time buyer conveyancing fees, as the legal team must spend more time verifying international banking systems. You'll likely need certified translations of foreign bank statements and proof that the money has been held in a regulated financial institution for a set period.
We understand that asking family for financial details can be awkward. Our team is here to act as a supportive bridge, providing clear instructions that make the process feel straightforward for your donors. If you want to ensure your family's contribution is handled with the respect and efficiency it deserves, get a transparent quote for your purchase today.
Why Choose Eagle Haus for Your Gifted Deposit Purchase?
Choosing the right legal partner is about more than just finding someone to handle the paperwork. It's about finding a guide who understands the emotional and financial weight of your purchase. At Eagle Haus Conveyancing Consultants, we specialise in gifted deposit conveyancing, bringing a modern, tech-savvy approach to a traditional process. We don't just process files; we build relationships. We ensure both you and your donors feel secure and informed throughout the journey, using clear communication tools that fit your contemporary lifestyle.
Our team handles a wide range of property transactions with a proactive attitude. Whether you're a first-time buyer or an investor looking at company purchases, we have the depth of knowledge required to keep your case moving. We also manage more intricate scenarios like bridging loans, ensuring that even the most complex financing structures are handled with precision. This versatility makes us a trusted choice for families across the region who need a firm that can scale with their ambitions while remaining deeply human and accessible.
Our Presence in the West Midlands
We take great pride in our deep roots across Staffordshire, Wolverhampton, and Birmingham. Our local knowledge isn't just about geography; it's about understanding the specific search requirements in Walsall or the regional lender preferences in Cannock and Shropshire. We know how West Midlands property trends evolve and which local authorities are currently processing searches with the most efficiency. This local insight allows us to anticipate potential hurdles before they arise, ensuring a stress-free completion for you and your family. We're part of the community, and we're dedicated to helping local buyers secure their future with confidence.
Transparent Legal Support
Communication is the foundation of our service. We've replaced confusing legalese with clear, direct guidance from the very first day you instruct us. By organising anti-money laundering (AML) checks efficiently, we prevent the common delays that often plague gifted deposit conveyancing. We provide your donors with simple, step-by-step instructions that demystify professional processes. This makes it easy for them to provide the necessary evidence without feeling overwhelmed or interrogated. Our partnership with Taylor Rose ensures your transaction is backed by regulated expertise while maintaining the personal touch of a boutique consultancy. We're proactive, not reactive, which keeps your purchase moving at a steady, reassuring pace.
Start your journey with a quote from Eagle Haus Conveyancing Consultants today and experience a more supportive, modern way to buy your home.
Securing Your Future with Confidence
Using a gift to step onto the property ladder is an exciting milestone. By organising your documentation early and having open conversations with your donors about financial checks, you've already cleared the biggest hurdles. You now understand the vital difference between a gift and a loan, and you're prepared for the 2026 regulatory landscape. This proactive approach ensures your gifted deposit conveyancing proceeds smoothly, protecting both your mortgage offer and your family's peace of mind.
At Eagle Haus, we're here to guide you through every step of this journey. Our partnership with the regulated firm Taylor Rose provides the security you need, while our specialist knowledge of the West Midlands market ensures your local search and lender requirements are met with precision. We pride ourselves on a modern, supportive approach that takes the stress out of legal communication. Whether you're buying in Birmingham, Wolverhampton, or Staffordshire, we'll act as your dedicated partner from instruction to completion.
Ready to take the next step? Get a transparent conveyancing quote for your gifted deposit purchase and move one step closer to your new front door. We look forward to helping you make your home-buying dreams a reality.
Frequently Asked Questions
Do I have to pay Inheritance Tax on a gifted deposit in 2026?
You don't pay Inheritance Tax at the point of purchase, but the "7-year rule" is a vital consideration. If the donor survives for seven years after making the gift, it's usually exempt from tax. However, if they pass away within this period, the gift may be included in their estate for tax purposes. The current nil-rate band remains at £325,000 until 2031, so keep this threshold in mind when planning.
Can a friend gift me a deposit for a mortgage in the UK?
While it is possible, most UK lenders prefer gifts to come from immediate family members like parents or siblings. Gifts from friends are often viewed with more caution and may be restricted or rejected by certain mortgage providers. If a friend does provide the funds, expect your gifted deposit conveyancing process to involve much more rigorous checks on their financial history to satisfy anti-money laundering regulations.
How far back do solicitors check bank statements for a gifted deposit?
Most solicitors will ask to see between 3 and 6 months of transaction history. This standard requirement allows the legal team to verify the "Source of Funds" and ensure the money hasn't suddenly appeared from an unverified source. If the money has moved between multiple accounts, you may need to provide statements for all of them to create a clear, uninterrupted audit trail for the lender.
Does the person gifting the money need to be on the property deeds?
No, the person gifting the money should not be named on the property deeds. Lenders actually require the donor to sign a formal declaration stating they have no legal or beneficial interest in the home. This ensures that you are the sole owner and that the donor cannot claim any right to live in the property or receive a share of the sale proceeds in the future.
What happens if I don’t declare a gifted deposit to my solicitor?
If you don't declare the gift, you risk your mortgage offer being withdrawn and the entire transaction failing. Solicitors have a legal duty to report the true source of your deposit to the lender. Discovering an undeclared gift late in the process can be seen as mortgage fraud, leading to significant delays or even being blacklisted by certain financial institutions. Transparency is always the safest path.
Can I use a gifted deposit if I am buying through a limited company?
You can use a gift for company purchases, but the legal structure is slightly different. The funds are often treated as a gift to the director, who then introduces the money to the company as a director's loan. This requires specific documentation to ensure the company's accounts and the gifted deposit conveyancing records are both accurate. It's best to seek professional advice to ensure the tax implications are handled correctly.
Is there a limit on how much money can be gifted for a house deposit?
There is no legal limit on the amount someone can gift you for a house purchase. However, individual mortgage lenders often have their own internal caps or specific loan-to-value (LTV) requirements. Some lenders may insist that you provide at least 5% of the deposit from your own personal savings, even if the rest is a gift. Always check your specific lender's policy before proceeding.
Can I use a gifted deposit for a buy-to-let purchase?
Yes, it's possible to use a gift for a buy-to-let property, though the choice of lenders may be more limited. Some providers view buy-to-let transactions as higher risk and may have stricter rules about who can provide the gift. As with residential purchases, you must disclose the gift at the start of your application to ensure your conveyancer can complete the necessary compliance checks without delay.


Comments