First Time Buyer Conveyancing Fees: A Complete 2026 Guide

What if the most stressful part of buying your first home isn't finding the property, but the fear of a hidden legal bill arriving just before you get your keys? It's a common anxiety for many, especially when trying to calculate first time buyer conveyancing fees amidst a sea of confusing jargon and varying quotes. You want to feel excited about your new front door, not worried that a "cheap" solicitor might miss a vital detail or surprise you with unexpected costs at the final hour.
We understand that transparency is the only way to build real trust. You deserve to know exactly what you're paying for, from the professional legal work to those essential third party disbursements. This guide provides a clear, line by line budget for 2026, covering everything from the latest Land Registry tiers to current Stamp Duty relief thresholds. We'll show you how to spot quality service and avoid the pitfalls of "hidden" extras, giving you a professional roadmap that replaces confusion with total confidence.
Table of Contents
Navigating First Time Buyer Conveyancing Fees in 2026
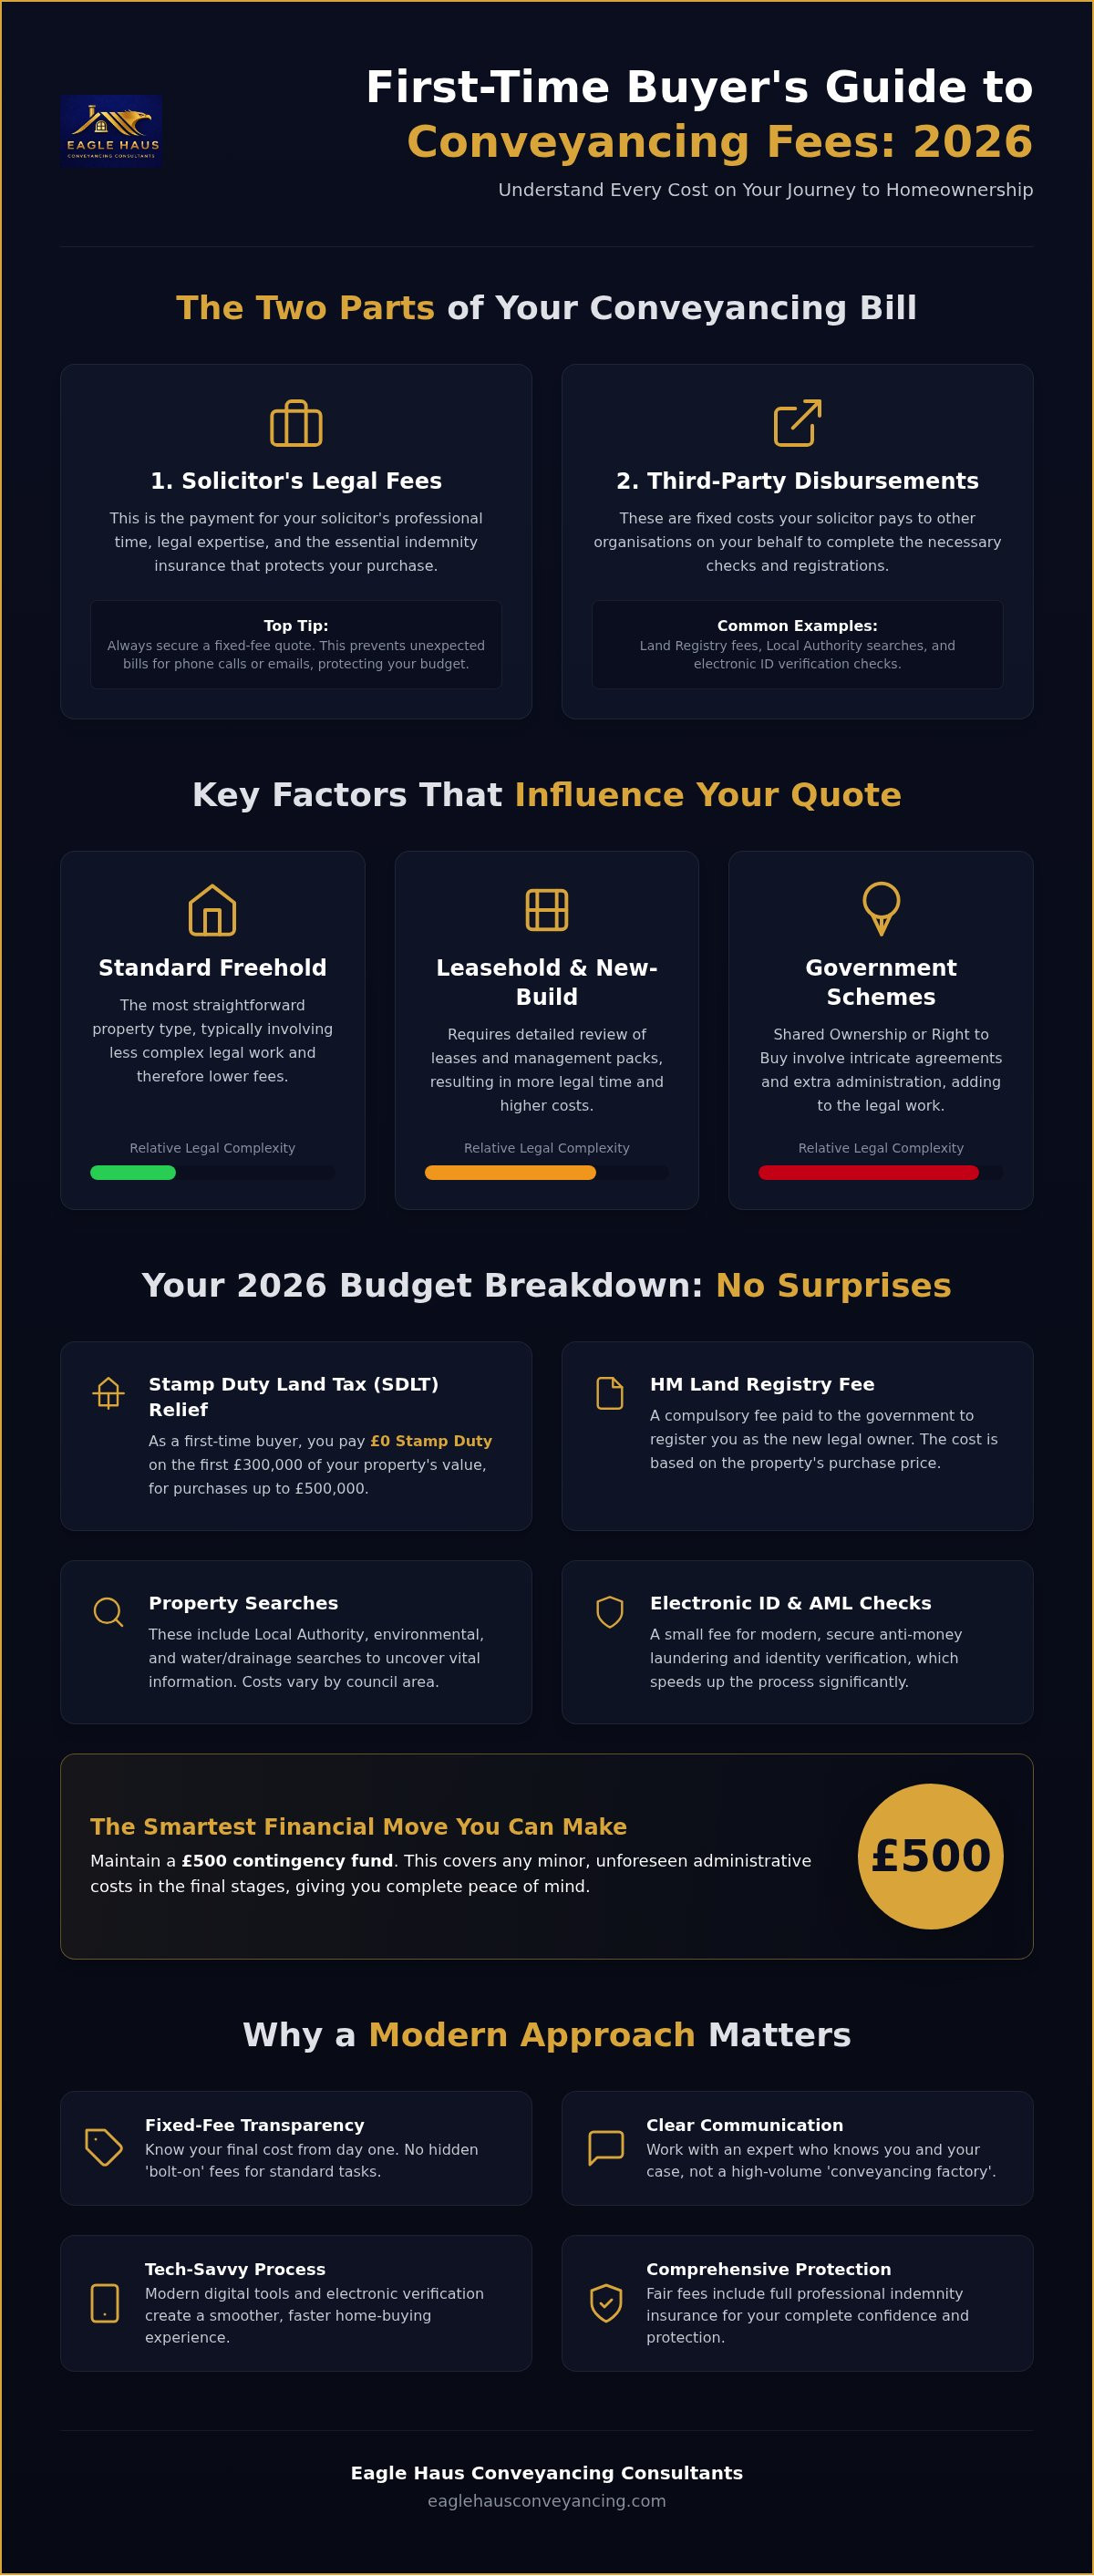
Many people experience "sticker shock" when they receive their final completion statement. The initial figure you see on a comparison website rarely reflects the total amount you'll pay at the end of the process. This happens because first time buyer conveyancing fees are split into distinct layers. You have the solicitor's professional fee for their time, but you also have third-party costs that the legal firm simply passes on to you. Understanding this distinction early prevents your budget from being blown apart at the last minute.
So, what exactly is happening behind the scenes? What is conveyancing? In short, it's the legal process of transferring home ownership from the seller to you. It involves checking title deeds, conducting local searches, and ensuring the money moves safely through the banking system. For those stepping onto the ladder for the first time, this process often involves extra steps like verifying gifted deposits from parents or managing Lifetime ISA (LISA) withdrawals. These unique requirements are why your quote might look slightly different from someone who is simply moving house.
Securing a fixed-fee quote is the most effective way to protect your hard-earned deposit. Without it, you might find yourself billed for every phone call or email, which quickly erodes your moving-day budget. By locking in a price at the start, you can focus on the excitement of your purchase rather than worrying about a ticking clock.
Why 'Cheap' Quotes Can Be Expensive
It's tempting to choose the lowest price you find online. However, "conveyancing factories" often handle hundreds of cases at once, leading to communication breakdowns and high stress. These low-cost providers frequently use "bolt-on" fees to make up their margins. You might be charged extra for basic tasks like filing a Stamp Duty return or verifying your identity. A fair, transparent fee usually includes comprehensive professional indemnity insurance and the dedicated time of an expert who actually knows your name and your specific situation.
Conveyancing for Shared Ownership and Right to Buy
If you are using a specific 2026 government scheme, the legal work becomes more intricate. Shared ownership involves complex leasehold agreements that require careful scrutiny to protect your future rights to "staircase" or increase your share. Similarly, Right to Buy purchases involve specific interactions with local councils that can add layers of administration. You need a partner who understands these nuances to ensure your path to homeownership remains smooth and predictable. Getting the right advice on first time buyer conveyancing fees for these schemes ensures you aren't overpaying for the extra work involved.
Legal Fees vs. Disbursements: What Are You Actually Paying For?
Think of your conveyancing quote as two separate pots of money. The first pot covers the legal fees, which is the payment for your solicitor's professional time, their years of expertise, and the essential indemnity insurance that protects your purchase. The second pot is for disbursements. These are third-party costs your solicitor pays to other organisations on your behalf to keep the process moving. Understanding this split in first time buyer conveyancing fees is the first step to budgeting with total confidence.
By 2026, the "digital shift" has transformed how these costs are presented. You'll likely see fees for electronic ID verification and Anti-Money Laundering (AML) checks as standard items. While these might feel like extra admin, they're vital security measures that replace the old, slow process of posting physical passports and utility bills. When you read a quote, look for a clear breakdown. If a firm bundles everything into one "all-in" figure without explaining the disbursements, it's much harder to know if you're getting a fair deal.
One of the most significant figures you'll see in your breakdown is Stamp Duty Land Tax (SDLT) relief. In 2026, first-time buyers in England and Northern Ireland don't pay any Stamp Duty on the first £300,000 of a property's price, provided the total purchase is under £500,000. This is a huge saving, but your solicitor still has to file the return to claim it, which is why a small administrative fee often appears for this task.
Common Disbursements Every First Time Buyer Should Know
Local Authority Searches are the most common disbursement. These prices vary depending on where you're buying; a search in Staffordshire might cost a different amount than one in the centre of Birmingham. You'll also see HM Land Registry fees. These operate on a sliding scale based on the property value. For an electronic application on a home priced between £200,001 and £500,000, the fee is currently £330. Other essential checks include environmental and drainage searches, which ensure your new home isn't at risk of flooding or built on contaminated land.
Anti-Money Laundering (AML) and Identity Checks
Solicitors have a strict legal duty to verify the source of your funds. This becomes slightly more complex if you have a "gifted deposit" from parents or relatives. In 2026, most firms use biometric apps to speed this up, allowing you to scan your face and documents on your smartphone. While there's usually a small fee for using these secure platforms, they significantly reduce the risk of fraud. If you want a partner who uses these modern tools to keep your move on track, you can request a transparent, fixed-fee quote that explains every check in plain English.
Key Factors That Affect Your Conveyancing Quote
Your property choice dictates a large portion of your final bill. While a standard terraced house might seem straightforward, the legal structure behind it changes how much work your solicitor must perform. This is why first time buyer conveyancing fees aren't a flat rate across the board. If you're looking at a home in an area like Shropshire, the property's value tier might also push you into a different Land Registry bracket. For example, properties priced between £200,001 and £500,000 attract a £330 registration fee for electronic applications, which directly impacts your total disbursements.
Mortgage lenders also play a role. Your solicitor doesn't just represent you; they represent the bank too. If your lender has specific, non-standard requirements for the title or requires extra searches, your legal team must spend more time satisfying those conditions. Buying a new build property often carries a premium in legal costs. Developers use their own bespoke contracts that require intense scrutiny. Your solicitor has to verify that the roads are adopted, planning permissions are fully compliant, and that new utility connections are properly registered. This extra layer of due diligence is essential to protect your investment.
Leasehold Complexities and Management Pack Fees
Choosing a flat or an apartment usually means buying a leasehold property. This adds significant complexity because your solicitor must review the lease agreement, check the length of the term, and investigate ground rent and service charges. You'll likely encounter management pack fees. These are charged by the freeholder or management company to provide essential information about the building's insurance and maintenance history. You should also budget for notice of transfer fees and deed of covenant costs, which are standard for leasehold transactions in 2026. These administrative costs often make leasehold transactions more complex than freehold ones due to the extra hours of legal scrutiny required.
Help to Buy and ISA Admin Fees
Many first-time buyers use a Lifetime ISA (LISA) to boost their deposit. While the government bonus is a massive help, it does involve additional paperwork for your legal team. Most firms charge a modest administrative fee to handle the specific withdrawal forms and verify the bonus with the provider. It's also vital to ensure your solicitor is on your specific mortgage lender's approved panel. If they aren't, they may have to outsource part of the work to another firm, which can add both time and expense to your first time buyer conveyancing fees. This is why checking your solicitor's credentials early in the process is so important.
Practical Budgeting: Planning for Every Property Cost
Effective budgeting for your first home requires looking far beyond the purchase price. One of the most critical elements to get right is your calculation for Stamp Duty Land Tax (SDLT). In 2026, first-time buyers in England and Northern Ireland benefit from significant relief, paying 0% on the first £300,000 of the property's price. If your home costs between £300,001 and £500,000, you'll pay a 5% rate on that specific portion. Understanding these thresholds ensures you aren't caught off guard by a tax bill that could otherwise run into thousands of pounds.
We always recommend that our clients set aside a "Contingency Fund" of at least £500. While your initial quote for first time buyer conveyancing fees will be as accurate as possible, the legal process can sometimes reveal the need for additional specific searches. For instance, a search might suggest a risk of local mining activity or historical chancel repair liabilities that require further investigation or indemnity insurance. Having this small buffer prevents these minor hurdles from causing major financial stress during the final weeks of your purchase.
When you compare quotes, look for value rather than just the lowest headline figure. A "cheap" quote often excludes essential tasks like filing your SDLT return or managing the bank transfer of your mortgage funds. To find the best value, ensure every quote you review is "like-for-like" and includes a full breakdown of both legal fees and third party disbursements. This transparency is the only way to guarantee that the price you're quoted at the start is the price you'll actually pay.
The Timeline of Payments
You don't pay your entire legal bill in one go. The "Instruction" phase usually requires a small upfront payment to cover the cost of your initial local authority and environmental searches. The next major milestone is the "Exchange of Contracts," which is when you'll need to provide your full deposit, typically 10% of the purchase price. Finally, on completion day, your solicitor will collect the remaining balance. This includes the final legal fees, Land Registry registration costs, and any Stamp Duty owed to HMRC. This staged approach helps you manage your cash flow throughout the move.
Budgeting for Surveys and Valuations
It's important to remember that a HomeBuyer Report or a full structural survey is a separate cost from your conveyancing fees. While your solicitor handles the legal title, a surveyor examines the physical condition of the building. Sometimes, legal findings in the searches might trigger the need for further specialist surveys, such as a damp report or an electrical inspection. For a deeper look at how these elements fit together, read our guide on Residential Purchases and Sales: A Modern Guide to Conveyancing in 2026. If you're ready to start your journey with a clear, honest budget, you can get a fixed-fee quote from our expert team today.
Why a Modern Approach to Conveyancing Matters for First Time Buyers
Choosing a legal partner is about finding someone who balances technical skill with genuine empathy for your situation. Eagle Haus Conveyancing Consultants operates with a philosophy that puts your peace of mind first. We know that the journey to your first home is filled with questions, especially regarding the total first time buyer conveyancing fees you'll encounter. By partnering with the regulated firm Taylor Rose, we offer the security of a large organisation with the personalised, boutique feel of a local consultant who is invested in your success.
Modern property markets in areas like Staffordshire and Wolverhampton move quickly. To keep pace, Eagle Haus Conveyancing Consultants uses digital-first communication and biometric identity verification to cut out weeks of postal delays. This proactive approach ensures that your file doesn't sit on a desk waiting for a physical signature. Instead, we use secure apps to move the process forward, helping you reach completion day faster without compromising on the legal rigour your purchase requires. It's a method designed to fit into your lifestyle, allowing you to track progress from your smartphone.
Local Expertise Across the West Midlands
Knowing the local landscape in Cannock, Walsall, and Telford provides a significant advantage during the legal process. Every local authority has different turnaround times for searches, and some areas have specific environmental or historical risks that require expert knowledge. Eagle Haus Conveyancing Consultants understands these regional nuances, allowing us to manage expectations and provide realistic timelines from the very start. This local insight ensures your first time buyer conveyancing fees are invested in a service that truly understands the ground beneath your new home and the specific requirements of West Midlands councils.
Next Steps for Your Property Purchase
Speeding up your move starts with preparation. You should gather your "Source of Funds" evidence, such as bank statements and proof of gifted deposits, before you even find your perfect property. The best time to instruct your solicitor is the moment your offer is accepted. By acting quickly, you give Eagle Haus Conveyancing Consultants the time to perform initial checks and request searches early, putting you in the strongest possible position to meet your target completion date. Taking these steps early reduces the pressure during the final stages of the transaction.
If you are ready to move forward with a partner who prioritises transparency and speed, we are here to support you. Start your journey with a transparent conveyancing quote from Eagle Haus Conveyancing Consultants and discover how our modern approach simplifies your path to homeownership.
Ready to Secure Your New Front Door?
Securing your first property is a landmark achievement that shouldn't be overshadowed by financial uncertainty. By understanding the breakdown of first time buyer conveyancing fees, you've already removed the biggest hurdle to a stress-free move: the fear of the unknown. You now have the tools to evaluate quotes like-for-like and the foresight to maintain a contingency for those essential third-party searches. This preparation ensures that when completion day arrives, you can focus on your new life rather than an unexpected invoice.
Eagle Haus Conveyancing Consultants is committed to making this transition as smooth as possible. Through our partnership with the regulated firm Taylor Rose, we combine specialist first-time buyer support across the West Midlands with a modern, digital-first communication style. This methodology isn't just about speed; it's about providing a sense of security through every milestone of your purchase. If you're ready to proceed with a legal partner who prioritises transparency, you can get a transparent, fixed-fee conveyancing quote for your first home from Eagle Haus Conveyancing Consultants today. We look forward to helping you turn those keys for the very first time.
Frequently Asked Questions
What is the average solicitor fee for a first-time buyer in 2026?
Average legal fees for buying a home in 2026 typically range between £400 and £1,500 depending on the property's complexity and value. This professional fee covers the expertise of your solicitor and their indemnity insurance. You should remember that this figure represents the legal work alone and does not include third-party disbursements or taxes like Stamp Duty, which are listed separately on your quote.
Do first-time buyers pay less in conveyancing fees?
First-time buyers don't necessarily pay lower legal fees, but they often benefit from significant tax savings. While the solicitor's time spent on the transaction is similar to other buyers, first time buyer conveyancing fees are often offset by Stamp Duty relief on properties up to £500,000. However, if you're using a Lifetime ISA or a gifted deposit, your legal bill might include small administrative supplements for the extra paperwork involved.
Are there hidden costs in a conveyancing quote?
Most reputable firms provide a fixed-fee quote, but costs can rise if the initial information provided was incomplete. Common extras that might feel "hidden" often include fees for bank transfers, identity checks, or acting on behalf of your mortgage lender. To avoid surprises, always ask for a full breakdown that includes every likely administrative charge and check if your quote includes a "no-move, no-fee" guarantee.
What are disbursements and why do I have to pay them?
Disbursements are essential third-party costs that your solicitor pays to other organisations on your behalf to complete the purchase. These include local authority searches, environmental reports, and Land Registry fees, which ensure the property is legally sound. These costs are passed through directly to you without any profit margin for the law firm, forming a necessary part of your total first time buyer conveyancing fees.
Do I pay my solicitor fees upfront or at the end?
You'll typically pay for your property searches upfront when you first instruct your solicitor, while the remaining legal fees are settled upon completion. The initial payment covers the immediate costs of requesting local authority data from the council. The bulk of the professional fee and any Stamp Duty are then collected as part of the final completion statement just before you get your keys.
Will my fees be higher if I am buying a Shared Ownership property?
Legal fees are generally higher for Shared Ownership properties because the solicitor must review a complex lease and liaise with a housing association. This additional work involves checking "staircasing" provisions and ensuring the lease meets your mortgage lender's specific requirements. You should expect to pay a supplement for this expertise, as the legal scrutiny required is more intensive than a standard freehold purchase.
What happens to my fees if the house sale falls through?
If your purchase falls through, you'll still be liable for any disbursements already paid, such as the cost of searches. Whether you pay the solicitor's professional fee depends on your agreement; many modern firms offer a "no-completion, no-fee" arrangement. If this isn't in place, you may be charged "abortive costs" based on the amount of work completed up to the point the transaction collapsed.
Is Stamp Duty included in my conveyancing quote?
Stamp Duty is not usually included in the initial "legal fee" headline, but it will appear on your final completion statement. Your solicitor calculates the tax owed and handles the payment to HMRC on your behalf within 14 days of completion. In 2026, many first-time buyers pay £0 in Stamp Duty on the first £300,000 of their purchase price, provided the property value doesn't exceed £500,000.
Comments