Bridging Loan Solicitors: A Case Study in Rapid Property Finance Completion

In the fast-moving world of bridging finance, every hour your solicitor spends "reviewing the file" is effectively a surcharge on your interest rate. When you're facing a strict 28-day auction deadline or a time-sensitive refurbishment, the difference between a generalist and specialist bridging loan solicitors can be measured in thousands of pounds. It's a high-stakes environment where even a single day of silence from your legal team can put your entire deposit at risk.
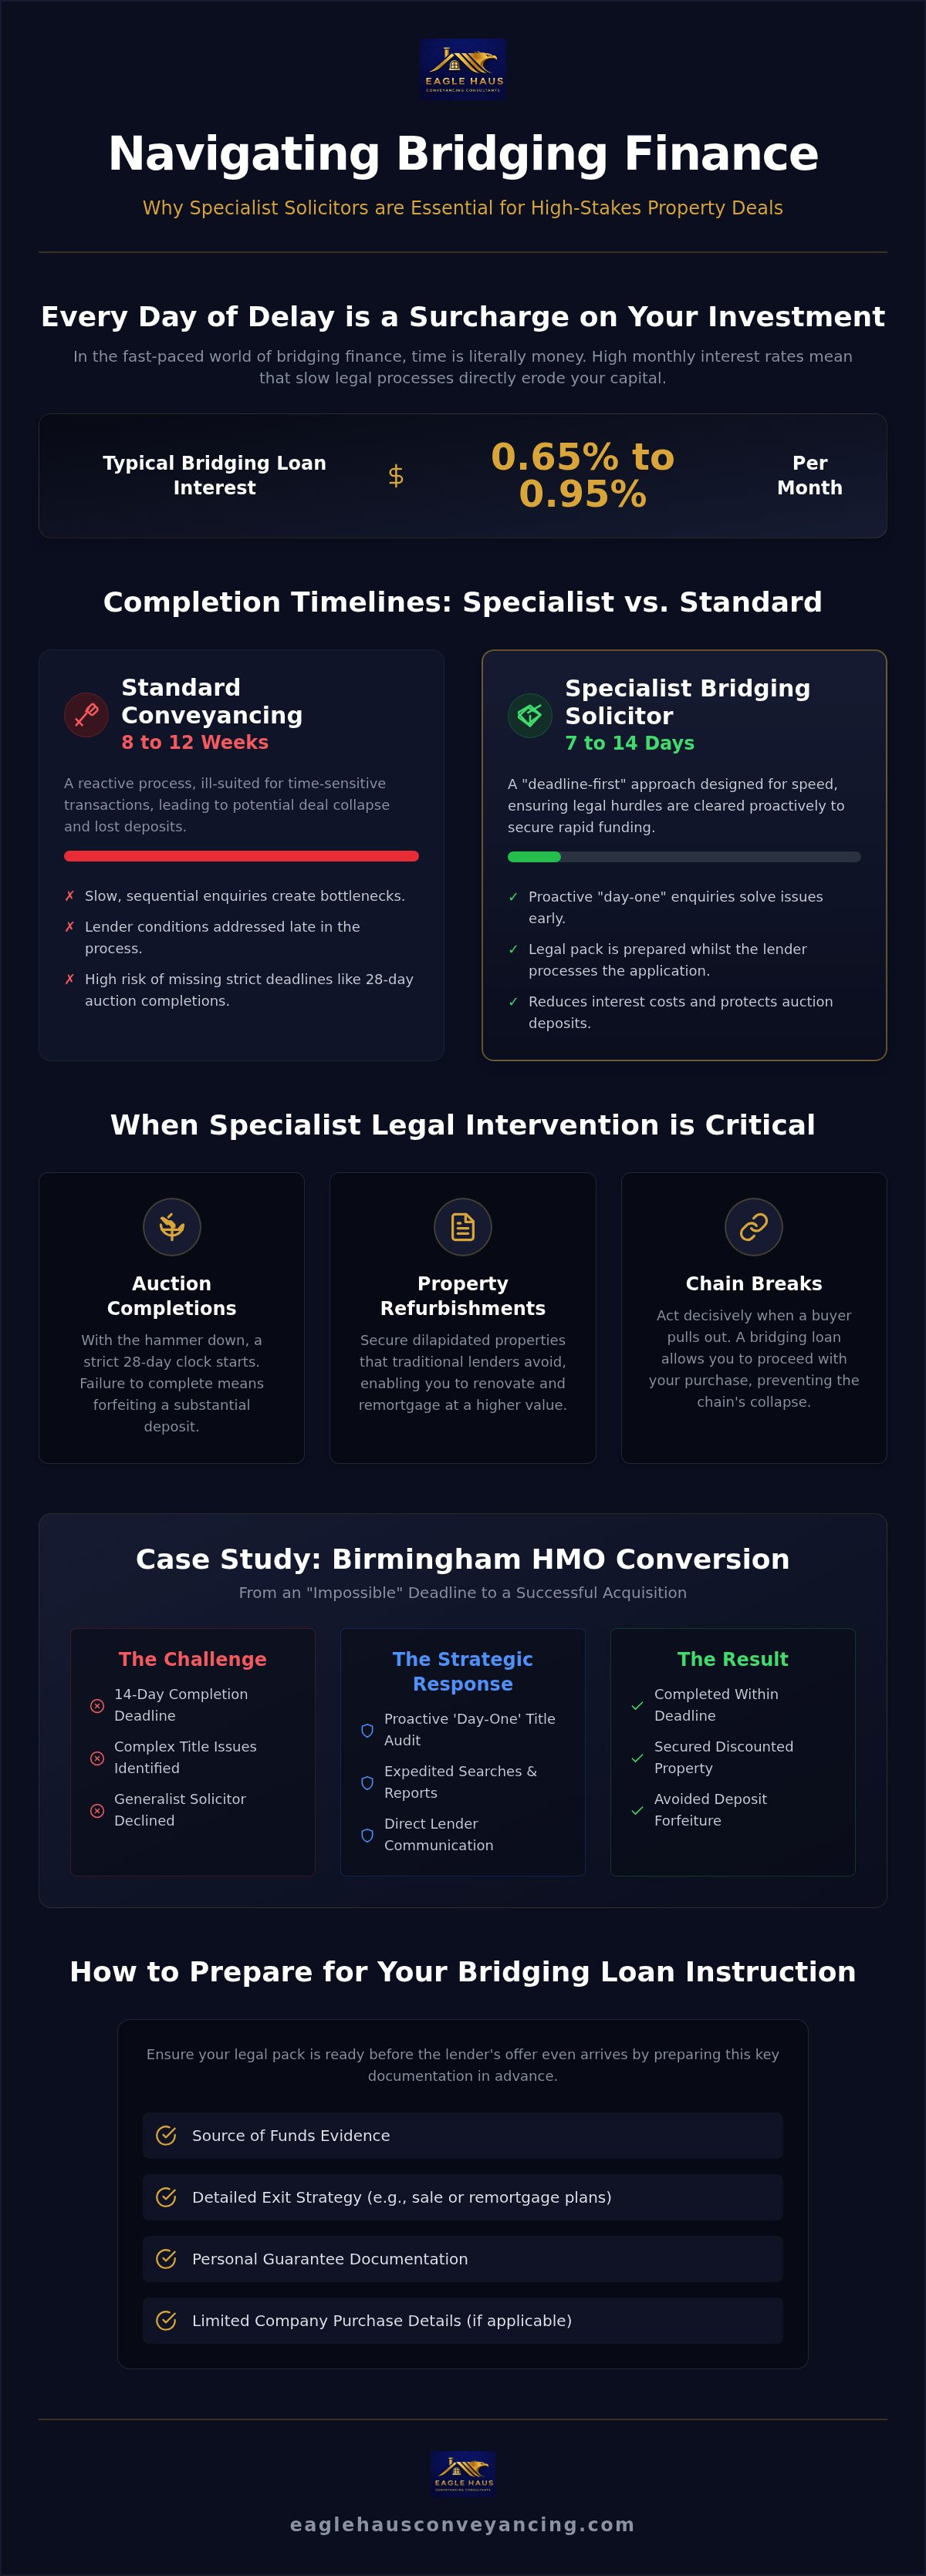
We understand that the pressure of mounting interest rates, often between 0.65% and 0.95% per month in the current market, makes traditional legal timelines feel painfully slow. You need a partner who treats your completion date as a hard deadline, not a suggestion. This article demonstrates how expert legal guidance secures rapid funding within 7 to 14 days whilst ensuring your property interests remain fully protected through a transparent, fixed-fee structure.
We will explore a real-world scenario where proactive communication and technical expertise pre-empted lender requirements, turning a potential delay into a seamless completion. By the end, you'll know exactly how to choose a legal partner who moves as quickly as your opportunities do.
Table of Contents
The Role of Bridging Loan Solicitors in Fast-Paced Property Deals
A bridging loan serves as a short-term, high-interest secured loan that provides immediate capital for time-sensitive transactions. It's often used as a financial bridge until a longer-term funding solution or a property sale is finalised. Because interest is calculated monthly, often between 0.65% and 0.95% in the current market, speed is the most critical factor. Standard legal workflows often buckle under this pressure. Specialist bridging loan solicitors operate with a "deadline-first" mindset, ensuring that legal hurdles don't erode your investment capital through avoidable delays.
Bridging vs. Standard Residential Conveyancing
Standard conveyancing typically follows an 8 to 12 week rhythm. In contrast, bridging finance often requires completion within a 7 to 14 day window. This intensity is driven by lenders who are significantly more risk-averse than traditional mortgage providers. They often require extensive documentation, personal guarantees, and detailed exit strategies. Because the timeline is so tight, bridging solicitors must prioritise "day-one" enquiries to address title issues or lender conditions immediately rather than waiting for the final stages of the process.
Typical Scenarios Requiring Urgent Legal Intervention
Several situations demand the rapid-response capability of a specialist legal team. These scenarios often involve high stakes where delay isn't just frustrating; it's expensive.
Auction completions: When the hammer falls, you typically have 28 days to pay the balance. Failure to do so means losing a substantial deposit.
Property refurbishments: Investors often use bridging to buy dilapidated properties that traditional lenders won't touch, intending to remortgage once the work is finished.
Chain breaks: If a buyer pulls out of a chain, a bridging loan allows you to proceed with your purchase, preventing the loss of your dream home or a lucrative investment.
Proactive title checking is where specialists truly add value. By identifying restrictive covenants or access issues early, your solicitor can solve problems while the lender is still processing the application. This proactive behaviour ensures that when the offer is issued, the legal pack is already sitting on the lender's desk, ready for sign-off. It's about moving at the speed of the market, not the speed of the paperwork.
Case Study: Securing a Commercial Refurbishment in Birmingham
A property investor recently approached us with a high-stakes opportunity in the West Midlands. They'd identified a dilapidated terrace in Birmingham, perfectly suited for conversion into a high-yield House in Multiple Occupation (HMO). The seller offered a significant discount, provided the investor could complete the purchase within 14 days. In such a high-pressure environment, the choice of bridging loan solicitors becomes the deciding factor between a successful acquisition and a forfeited deposit.
The Problem: A 14-Day Completion Deadline
The investor faced immense pressure. Under the terms of the private treaty sale, failing to complete within a fortnight meant losing a 10% deposit and missing out on the property's discounted valuation. Their usual generalist solicitor declined the instruction, stating the timeline was impossible for a property with potential title complexities. This is a common hurdle; many firms lack the "day-one" urgency required for bridging. Our deep knowledge of the Birmingham and Wolverhampton property markets allowed us to identify potential local planning restrictions and title defects within the first 24 hours of instruction.
Standard conveyancing often gets bogged down in back-and-forth enquiries that aren't critical to the immediate security of the loan. For this Birmingham project, the investor needed a legal team that could distinguish between a deal-breaking title defect and a minor administrative hurdle. Without this distinction, the 14-day clock would have run out long before the final contracts were exchanged.
The Strategic Legal Response
Eagle Haus operates as a trading name of TRW Legal Consulting Ltd, delivering services through Taylor Rose. This structure allowed us to combine boutique, local attention with the national resources needed to expedite searches. We performed an immediate audit, identifying minor title defects that would usually stall a standard purchase for weeks. By opening a direct line of communication with the lender's legal team, we successfully negotiated the waiver of non-critical enquiries that didn't impact the lender's security. This proactive behaviour is what separates specialists from generalists.
Understanding the wider financial context is also vital for investors. While focusing on speed, we ensured the client was aware of relevant tax rules for bridging loans and how their exit strategy would satisfy the lender's long-term requirements. We didn't just push paper; we managed the risk. The result was a successful completion in just 11 days, three days ahead of the deadline. If you're currently facing a tight deadline, our team can help you secure your bridging finance with the same proactive approach, ensuring your capital is put to work without unnecessary delay.
Navigating the Legal Hurdles of Bridging Finance
Unlike some traditional firms that view short-term finance as a high-risk gamble, we see it as a sophisticated investment tool for those who know how to use it. The legal process isn't just about filing paperwork; it's about satisfying the lender's "Condition of Offer" before high interest costs begin to mount. Specialist bridging loan solicitors must be adept at balancing this extreme speed with the meticulous due diligence that protects your long-term interests.
The First 48 Hours: The Make-or-Break Window
The success of a bridging deal is often decided in the first two days. We prioritise ID verification and source of funds checks on day one because these administrative tasks often cause the longest delays if left until later. If a local authority search has a six-week lead time, we'll suggest title insurance or "Fast Track" search products immediately to keep the momentum. Identifying "Red Flags" like restrictive covenants or missing building regulations early allows us to address them before the lender's valuer even visits the site, preventing a "subject to" offer from stalling.
Company Purchases and Limited Company Bridging
Many modern investors now use Special Purpose Vehicles (SPVs) for tax efficiency. This adds a layer of corporate legal work to the property transaction. We specialise in company purchases, ensuring the corporate structure meets the lender's strict security requirements. This often involves providing Independent Legal Advice (ILA) for directors who are giving Personal Guarantees (PGs). Our approach to conveyancing for property investment companies ensures that every director's obligation is clearly explained and documented without slowing down the transaction pace.
Every bridging lender requires a robust exit strategy. This isn't just a financial plan; it's a legal requirement that must be documented within the loan agreement. Whether you're planning a property sale or a remortgage, your solicitor must prove the feasibility of this exit to the lender. It's also important to distinguish between unregulated investment loans and FCA regulated bridging loans, as the legal protections and documentation requirements differ significantly. Clear communication about these hurdles ensures you aren't caught off guard by the lender's final requirements just as you're ready to complete.
How to Prepare for Your Bridging Loan Instruction
Successful bridging finance depends on a synchronised effort between the borrower and their legal team. Whilst we handle the technical complexities, your proactive preparation can shave days off the timeline. The goal is to be "legally ready" the moment the lender's offer hits our desk. This means collating your identity documents and source of funds evidence well in advance. Most delays in bridging aren't caused by complex law; they're caused by missing bank statements or unverified ID.
You must also ensure your exit strategy is legally documented. Whether you intend to sell the property or transition to a traditional remortgage, having these plans in writing satisfies the lender's primary concern: how they'll get their money back. Instructing proactive bridging loan solicitors early in the process ensures these details are polished before they become a bottleneck.
Checklist for a 7-Day Completion
To hit a one-week turnaround, you need to be organised from the start. We recommend having the following items ready before you even apply for the loan:
A confirmed memorandum of sale with full contact details for all legal parties involved.
A building insurance policy that's ready to be noted with the lender's interest.
Upfront funds for legal disbursements, such as local authority searches or Land Registry fees.
Paying for searches on day one is essential. If local authority timelines are too slow, we can often arrange indemnity insurance to keep the deal moving. This proactive behaviour ensures the legal pack is completed whilst the lender is still finishing their valuation.
Choosing the Right Bridging Loan Solicitor
Not all firms are equipped for the pace of bridging loans. You should verify that your solicitor is on your chosen lender's panel. If they aren't, the lender will appoint their own solicitor at your expense, which doubles the communication lines and the cost. Ask about their dedicated points of contact; you don't want your file sitting in a general pool where no one takes ownership of the deadline.
Local expertise in areas like Staffordshire, Shropshire, or the Black Country adds significant value. We understand the specific nuances of regional valuations and local authority quirks, which helps us pre-empt issues that a distant firm might miss. Our team is ready to help you prepare your bridging instruction today, ensuring your property goals stay on track without unnecessary stress.
Why Eagle Haus is the Strategic Choice for Bridging Finance
Choosing the right legal partner shouldn't be a gamble when your deposit is on the line. When you search for bridging loan solicitors, you aren't just looking for someone to sign documents; you're looking for a strategic partner who understands that time is your most expensive commodity. Eagle Haus provides a unique blend of boutique, personalised service from our Staffordshire roots, backed by the national reach and regulated excellence of Taylor Rose. As a trading name of TRW Legal Consulting Ltd, we deliver our services through Taylor Rose to ensure you receive the highest standard of professional care.
Transparency is at the heart of our modern approach. We operate on a clear, fixed-fee structure, ensuring you know exactly what your legal costs will be from the outset. Unlike some firms that might add hidden "urgency surcharges" when a deadline nears, we believe that speed should be a standard feature of bridging finance, not an expensive extra. By removing financial ambiguity, we allow you to focus on the numbers that matter: your investment returns.
We leverage modern communication methods to ensure your deal never stalls due to "postal delays" or administrative silences. We use tech-savvy workflows to facilitate digital document signing and rapid identity verification, keeping the momentum high from instruction to completion. This proactive attitude means we don't just react to lender enquiries; we anticipate them. We treat your completion date as our own hard deadline, providing the momentum needed to secure your property assets.
The Eagle Haus Advantage
Our firm is built specifically to support property investors and developers who require more than just standard conveyancing. We organise the legal process by performing early-stage title audits and search reviews, which allows us to pre-empt the specific enquiries that bridging lenders typically raise. We are committed to providing reassuring, professional, and modern guidance that simplifies the complex legal landscape for property investors, ensuring you feel supported at every stage of the transaction.
Next Steps: Securing Your Property Finance
Securing your next property opportunity starts with a clear legal roadmap. When you request a tailored quote from us, we provide a comprehensive breakdown of the steps required to meet your specific completion window. During your initial 30-minute consultation, we'll discuss your exit strategy, any potential title "red flags," and the lender's specific requirements to ensure we can hit the ground running.
Don't let legal delays erode your investment potential or put your auction deposit at risk. Our team is ready to provide the rapid, expert support your project deserves. Contact us today for a tailored quote and take the first step toward a seamless, fast-paced completion.
Move Forward with Confidence on Your Next Property Deal
Securing a property in a competitive market requires more than capital. It requires a legal team that moves at the same pace as your investment opportunities. The Birmingham case study demonstrates how specialist West Midlands knowledge and proactive title checking turn potential auction disasters into successful completions. By preparing documentation early and choosing bridging loan solicitors who understand short-term finance, you protect your deposit and your reputation as a reliable buyer.
At Eagle Haus, we combine local expertise with the national resources of Taylor Rose to ensure regulated excellence. Our commitment to fixed-fee transparency means you can calculate returns with certainty, knowing there are no hidden costs waiting at the finish line. Whether you're converting a terrace in Birmingham or saving a residential chain, we're here to act as your modern professional guide.
If you're ready to secure your next asset, contact Eagle Haus for a professional bridging loan quote. Let's make your property goals a reality with speed and security.
Frequently Asked Questions
How long does the legal process for a bridging loan take?
The legal process for a bridging loan typically takes between 7 and 14 days from instruction to completion. This is significantly faster than the 8 to 12 weeks usually seen in standard residential conveyancing. Preparation is the most critical factor in hitting these tight deadlines. Having your ID and source of funds evidence ready on day one allows us to match the lender's urgency whilst ensuring your interests remain protected.
Why do bridging loan solicitors cost more than standard conveyancers?
The higher cost reflects the intensity of the work and the significantly shorter timescales involved. Bridging instructions require solicitors to prioritise your deadline above all else, often working within a fortnight rather than several months. The complexity is also greater, involving more stringent lender requirements, personal guarantees, and detailed exit strategies. Standard residential transactions simply don't require this level of rapid-response legal expertise or the same volume of technical documentation.
What is Independent Legal Advice (ILA) in bridging finance?
ILA is a mandatory requirement where a solicitor who isn't acting for the borrower explains the risks of a personal guarantee to a director or third party. Lenders insist on this to ensure the person signing understands they are personally liable if the loan isn't repaid. It's a vital safeguard that prevents later claims of "undue influence." Our team can coordinate this process quickly to ensure it doesn't stall your completion timeline.
Can I use the same solicitor for my bridging loan and the subsequent remortgage?
Yes, using the same solicitor for both the bridging loan and the exit remortgage is often the most efficient choice. Since your solicitor already has your title information, ID, and property details on file, the transition to long-term finance is much smoother. This continuity reduces administrative friction and ensures your legal team is fully aligned with your long-term investment strategy from the very beginning of the project.
Do I need a local bridging loan solicitor for a property in Birmingham?
Whilst not strictly mandatory, choosing a solicitor with specific West Midlands knowledge provides a distinct strategic advantage. Local bridging loan solicitors understand regional authority quirks and valuation nuances in Birmingham, Staffordshire, and Shropshire. This familiarity allows for much faster identification of potential title issues or planning restrictions that a distant firm might miss. We blend this boutique local insight with the national resources of Taylor Rose to expedite your transaction.
What happens if my bridging loan completion is delayed?
Delays can lead to significant financial penalties, especially in auction scenarios where you might forfeit your 10% deposit. Additionally, because bridging interest is calculated monthly, every day of delay increases your overall borrowing cost. Our proactive approach involves identifying potential legal hurdles in the first 48 hours and maintaining constant communication with the lender's legal team to pre-empt delays before they cause a costly breach of your purchase contract.
Is a bridging loan solicitor different from a standard property lawyer?
A bridging loan solicitor is a specialist who operates with a "deadline-first" mindset that differs from standard conveyancing. Standard property lawyers are often accustomed to the slower pace of the residential chain. In contrast, bridging specialists are trained to handle complex lender conditions, such as debentures and personal guarantees, within extreme timescales. We focus on "day-one" enquiries to ensure the legal pack is ready the moment the lender's offer is issued.
What are the common legal "red flags" that stop bridging loans from completing?
Common issues include restrictive covenants, missing building regulations for recent works, or complications with the exit strategy documentation. Lenders are particularly sensitive to anything that might affect their ability to sell the property if you default. Identifying these issues in the first 48 hours of instruction allows us to suggest solutions, such as indemnity insurance, to satisfy the lender without derailing your urgent completion timeline or risking your property investment.
Comments